Bitcoin's volatility makes Bitcoin ETFs unusually good tax-loss-harvesting candidates. Here is the mechanics, what the wash-sale rule actually says, and why its application here is unsettled.
TL;DR. Bitcoin ETFs in taxable accounts are good tax-loss harvesting candidates: bitcoin falls hard and often enough to leave losing lots in most years. The wash-sale rule of section 1091 disallows a loss if you rebuy "substantially identical" securities within 30 days. The IRS has never said whether a spot Bitcoin ETF falls inside that rule. There is no ruling or published guidance on the point, and the funds' own filings do not claim there is. The usual workaround is to swap issuers (IBIT → FBTC, IBIT → ARKB) instead of rebuying the same fund, and to match the dollar amount, not the share count.

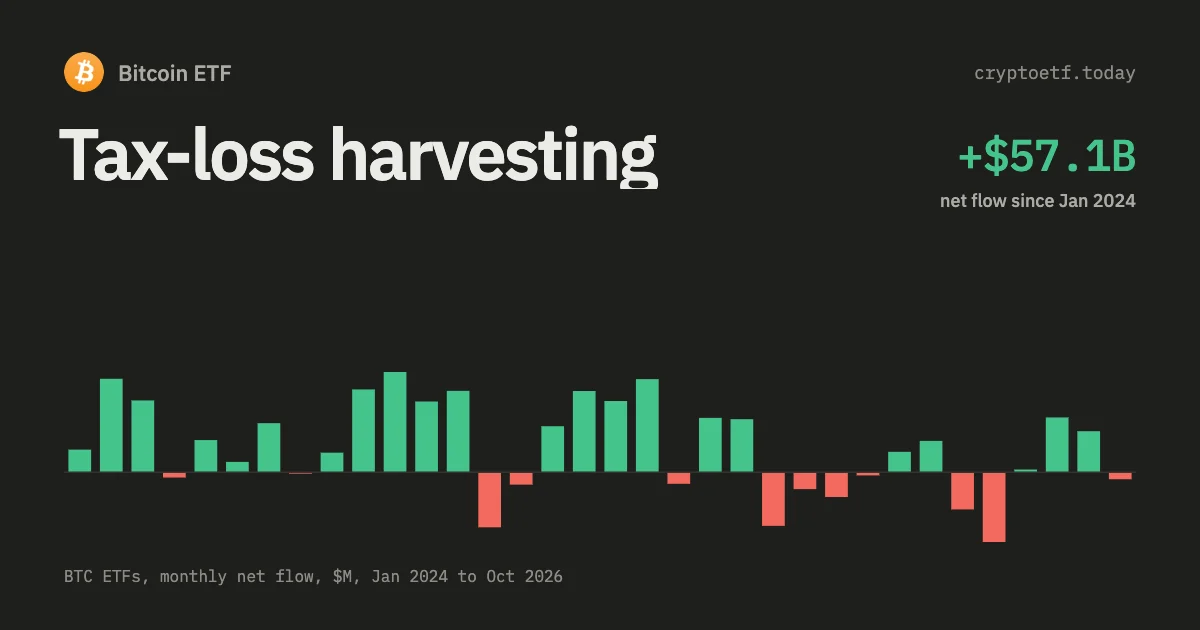
Bitcoin ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 9 sections
Why bitcoin ETFs are good harvest candidates
Bitcoin is far more volatile than a broad equity index. A diversified S&P 500 holding can go years without a harvestable loss. A bitcoin position usually offers several a year. On our own daily price series, three drawdowns landed inside eighteen months: −23.6% from 14 March to 8 July 2024, −20.5% in the eight days from 29 July to 6 August 2024, and −25.5% from 18 December 2024 to 11 March 2025.
So even a buy-and-hold investor who DCAs in regularly will, at various points, own lots that are under water. You sell them to realise the loss and immediately replace the exposure with a similar but not identical fund. You keep the tax benefit and never leave the market.
The mechanics of tax-loss harvesting
- Find the lots in your taxable account that are worth less than you paid.
- Sell those lots, realising the capital loss.
- Within minutes, buy a different fund that does the same job, so your market exposure stays put.
- The realised loss offsets capital gains elsewhere in your portfolio. If losses exceed gains, Publication 550 caps the deduction against other income at "$3,000 ($1,500 if you are married and file a separate return)".
- Anything above that limit carries forward: "you can carry it over to later years until it is completely used up."
At a 20% long-term capital gains rate plus the 3.8% net investment income tax, a $10,000 harvested loss used against long-term gains is worth about $2,380. Used against ordinary income instead, the $3,000 annual cap is worth $720 a year to someone in the 24% bracket.
The wash-sale rule — and why its application here is unsettled
Publication 550 states the rule plainly: "A wash sale occurs when you sell or trade stock or securities at a loss and within 30 days before or after the sale you: Buy substantially identical stock or securities…" The loss is postponed, not destroyed. You "add the disallowed loss to the cost of the new stock or securities".
Nobody has settled whether a spot Bitcoin ETF sits inside that rule, and a source that states it flatly is guessing. The IRS has issued no ruling or guidance on spot bitcoin grantor trusts and section 1091, and the issuers do not claim otherwise. BlackRock's 10-K for the iShares Bitcoin Trust ETF for fiscal 2025, filed 27 February 2026, never uses the words "wash sale", "substantially identical" or "section 1091". Its tax section is hedged even about the trust's own classification. Counsel's opinion is that the trust "should be classified as a 'grantor trust' for U.S. federal income tax purposes", "although not free from doubt due to the lack of directly governing authority".
What Publication 550 says about "substantially identical" is a facts-and-circumstances test written for corporate stock: "you must consider all the facts and circumstances in your particular case. Ordinarily, stocks or securities of one corporation are not considered substantially identical to stocks or securities of another corporation." A grantor trust holding bitcoin is not a corporation, and the publication does not address it.
In practice, assume the rule applies. If it does and you ignored it, you lose the deduction. If it does not and you followed it anyway, all you gave up was the chance to rebuy the same fund straight away. Bitcoin you hold directly, outside a fund, is a different case: it is property, not a security, and section 1091 does not cover it.
Swap fund pairings
The IRS has never ruled on whether two spot Bitcoin ETFs are substantially identical. The common working position is that funds from different sponsors are distinct enough even when they hold the same asset. That is a position, not a safe harbour. Pairings people use: IBIT ↔ FBTC, the cleanest, because Fidelity is the one issuer that holds its own bitcoin instead of using Coinbase; IBIT ↔ ARKB, different sponsors with overlapping custody; FBTC ↔ HODL, no custodian in common; and IBIT ↔ Grayscale Bitcoin Mini Trust, different sponsors and very different fees, 0.25% against 0.15%.
Don't rebuy the fund you just sold, and above all don't rebuy it inside an IRA. Publication 550 names that case: acquiring substantially identical stock "for your individual retirement arrangement (IRA) or Roth IRA" is a wash sale. It is also the one case left out of the basis adjustment, so the loss is not postponed. It is gone for good.
The numerical example
Scenario: a $50,000 IBIT position in a taxable account. Bitcoin falls and the position is now worth $40,000, a $10,000 unrealised loss.
- Sell the whole position, realising a $10,000 capital loss.
- Immediately buy $40,000 of FBTC: the same dollar amount, not the same number of shares. Each fund has a different share price, so matching share counts would change the size of your position, possibly several times over.
- Your market exposure is the same as before, and you now hold a $10,000 realised loss.
- At year end, offset it against $10,000 of capital gains elsewhere. That saves about $2,380 at 20% plus the 3.8% NIIT.
- With no gains to offset, deduct $3,000 against other income this year and carry $7,000 forward.
The bitcoin price can move between selling IBIT and buying FBTC. The gap is usually a few seconds, so the effect is small. It is not zero.
What to track
- Cost basis per lot. Check that your broker uses specific-lot identification, not FIFO, before you sell.
- The 61-day window: 30 days before the sale, 30 days after it, and the day of sale.
- IRA accounts. A repurchase inside your own IRA disallows the loss permanently.
- Spousal accounts. Publication 550: "If you sell stock and your spouse or a corporation you control buys substantially identical stock, you also have a wash sale."
Limits and caveats
- Harvesting does nothing inside a Roth or traditional IRA, because nothing is realised there. It only works in taxable accounts.
- Carryforwards last until used up, but they are personal. Unused capital loss carryovers do not pass to heirs.
- States differ in how closely they follow the federal rules. Check yours.
FAQ
Does the wash-sale rule apply to Bitcoin ETFs?
Nobody knows for certain. Section 1091 covers "stock or securities", and the IRS has never ruled on whether a spot bitcoin grantor trust fits that definition. BlackRock's 10-K for IBIT does not mention wash sales, substantially identical securities or section 1091 at all. Assume the rule applies. If you are wrong that way, it costs nothing; if you are wrong the other way, you lose the deduction.
Can I sell IBIT at a loss and buy FBTC the same day?
Many investors do, and the two funds have different sponsors, custodians and trust documents. But that is a working position, not a rule: the IRS has never ruled on whether two spot Bitcoin ETFs are substantially identical. Cautious investors wait 31 days.
Should I buy the same number of shares of the replacement fund?
No, match the dollar amount. Share prices differ a lot between spot Bitcoin ETFs, so an equal share count can leave you with a much larger or smaller position than you started with. Sell $40,000 of one fund, buy $40,000 of the other.
How much can I save with Bitcoin ETF tax-loss harvesting?
Roughly 23.8% of the loss (20% long-term capital gains plus the 3.8% net investment income tax) when offset against long-term gains, and more against short-term gains or ordinary income. Against other income the deduction is capped at $3,000 a year ($1,500 married filing separately). The rest carries forward until used up.
Can I tax-loss harvest in my Roth IRA?
No. Gains and losses inside a Roth or traditional IRA are not taxable events, so there is nothing to harvest. Worse, buying the same fund inside your IRA within 30 days of a taxable-account loss sale is the one wash-sale case where the disallowed loss is not added back to basis. You lose it permanently.
Sources and further reading
- IRS Publication 550, "Investment Income and Expenses": wash sales, substantially identical securities, and the capital loss deduction limit. irs.gov.
- iShares Bitcoin Trust ETF, Form 10-K for the year ended 31 December 2025, filed 27 February 2026. sec.gov.
- Internal: Bitcoin ETF tax in the USA, Bitcoin ETF in a Roth IRA, IBIT vs FBTC.
For information only. Not investment advice.

 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC