Holding a Bitcoin ETF inside a Roth IRA shelters all future gains from tax. The 2026 and 2027 limits, the compounding and fee math, and which funds are available.
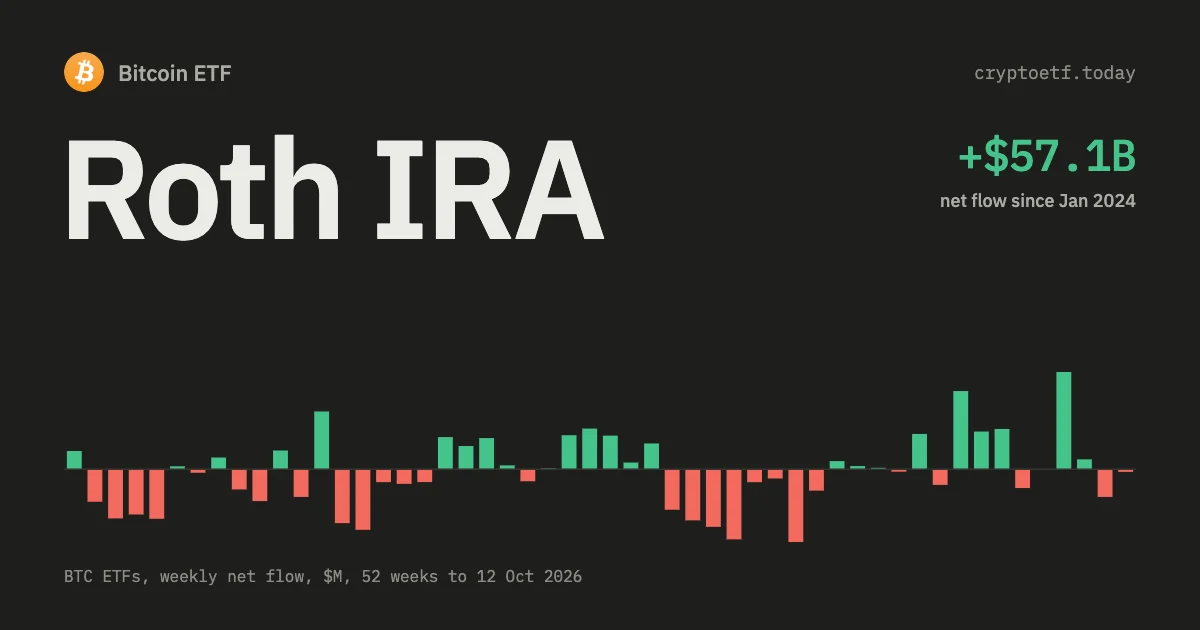

Bitcoin ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 11 sections
Updated 19 November 2026 with the IRS's 2027 limits (announced 12 November 2026) and fund data as of 17 November 2026. This is general information, not tax or investment advice; check your own situation with a tax professional.
TL;DR. The Roth IRA is the best wrapper for a long-term Bitcoin ETF position: contributions are after-tax, and all growth and qualified withdrawals are tax-free. The contribution limit is $7,500 for both 2026 and 2027, or $8,600 if you are 50 or older. 2026 contributions can still be made until 15 April 2027. The income phase-out rises for 2027 to $158,000–$173,000 for single filers and $250,000–$260,000 for married couples filing jointly (2026: $153,000–$168,000 and $242,000–$252,000). Above the phase-out, the usual route is a backdoor Roth conversion. Fees matter more than most people expect over decades: sponsor fees on US spot Bitcoin ETFs run from 0.14% to 1.50% a year. Every major US broker now supports spot Bitcoin ETFs in a Roth, Vanguard included since December 2025.
Why Roth specifically for Bitcoin ETFs
Bitcoin has historically delivered high but lumpy returns, which means a large capital gains bill at exit unless the position is sheltered. A Roth IRA shelters it completely:
- Contributions: after-tax dollars, no deduction.
- Growth: tax-free.
- Qualified withdrawals (age 59½ and the 5-year clock met): tax-free, and no required minimum distributions during the owner's lifetime.
Compare with a taxable account, where every sale is a realisation event: at a 20% long-term capital gains rate plus the 3.8% net investment income tax, a $300,000 gain carries roughly $71,400 of federal tax. In the Roth it is zero. That wrapper is also the main argument for choosing the ETF over coins in the first place, since a mainstream brokerage IRA cannot hold bitcoin directly — see Bitcoin ETF vs spot Bitcoin.
The 30-year math
An illustration, not a forecast. It assumes a flat $7,500 contribution and a steady 10% nominal return before fund fees, neither of which will happen in practice. $7,500 a year for 30 years is $225,000 contributed and grows to about $1.23M, of which roughly $1.01M is gain. In a Roth all of it is withdrawable tax-free. On the identical path in a taxable account, liquidating at 20% plus the 3.8% NIIT costs about $240,000 and leaves about $994,000.
Roth advantage: roughly $240,000, and the gap scales with the return assumption. That is why the asset you expect to grow fastest is the one worth sheltering.
Which fund to hold: fees compound too
Inside a Roth the tax question is settled, so the remaining cost you control is the sponsor fee. Run the same illustration with the fee taken out of the return each year: at 0.14% the account ends near $1.20M, at 0.25% near $1.17M, and at 1.50% near $0.91M. The gap between the cheapest and the most expensive fund is roughly $290,000 on $225,000 of contributions, and none of it comes back as a deduction in a Roth.
US spot Bitcoin ETFs as of 17 November 2026 (our fund data; FBTC net assets are estimated from coins and price because Fidelity does not publish daily holdings):
| Fund | Issuer | Sponsor fee | Net assets |
|---|---|---|---|
| IBIT | BlackRock | 0.25% | $50.09bn |
| FBTC | Fidelity | 0.25% | $11.11bn |
| GBTC | Grayscale | 1.50% | $7.82bn |
| BTC (Bitcoin Mini Trust) | Grayscale | 0.15% | $3.97bn |
| BITB | Bitwise | 0.20% | $2.34bn |
| ARKB | ARK / 21Shares | 0.21% | $1.80bn |
| HODL | VanEck | 0.20% | $0.91bn |
| MSBT | Morgan Stanley | 0.14% | $0.74bn |
| BRRR | CoinShares | 0.25% | $0.36bn |
| EZBC | Franklin Templeton | 0.19% | $0.34bn |
| BTCO | Invesco Galaxy | 0.25% | $0.32bn |
| BTCW | WisdomTree | 0.25% | $0.13bn |
Together the twelve funds held about $79.9bn and 1.25 million BTC. Fees change, and some issuers run temporary waivers, so check the current figure on the fund directory before buying. Size matters for trading costs as well: a large fund such as IBIT (price and premium page) usually trades with tighter bid-ask spreads, which counts for more if you add money monthly. GBTC kept a 1.50% fee when it converted from a closed-end trust to an ETF in January 2024. For a new Roth position there is no tax reason to prefer it, because switching funds inside a Roth triggers no capital gains.
One more point on timing. Daily creations and redemptions show when money is entering or leaving the funds (see the Bitcoin ETF flows dashboard), but a Roth funded once a year or monthly does not need to react to them. The flow data is more useful for understanding what moved the price than for picking an entry day.
Setup mechanics
Any major US brokerage (Fidelity, Schwab, E*TRADE, Interactive Brokers, Robinhood, Vanguard) opens a Roth IRA online in a few minutes against an SSN, employment details and a beneficiary designation. Fund it by ACH, typically one to three business days. Contributions for a tax year can be made up to the due date of that year's return, so 2026 contributions run through 15 April 2027, and 2027 contributions open on 1 January 2027. Between January and mid-April you can fund both years; tell the broker which year each deposit is for.
Once cash settles, place a limit order on your chosen fund (IBIT, FBTC, ARKB, EZBC, BITB, HODL and the rest). A Roth IRA holds the security exactly as a taxable account does; there is no special mechanic. See how to buy a Bitcoin ETF for the walkthrough.
Contribution limits and phase-outs (2026 and 2027)
The 2026 figures are from IRS Publication 590-A and the IRS 2026 cost-of-living tables. The 2027 figures are from IRS news release IR-2026-136 of 12 November 2026 and Notice 2026-66.
| 2026 | 2027 | |
|---|---|---|
| Contribution limit | $7,500 | $7,500 (unchanged) |
| Catch-up at 50 or older | $1,100 (total $8,600) | $1,100 (total $8,600) |
| Phase-out, single or head of household (MAGI) | $153,000–$168,000 | $158,000–$173,000 |
| Phase-out, married filing jointly (MAGI) | $242,000–$252,000 | $250,000–$260,000 |
| Phase-out, married filing separately (lived with spouse) | $0–$10,000 | $0–$10,000 (not inflation-adjusted) |
Below the bottom of the range you can contribute the full amount; inside it the allowed amount shrinks; at the top it is zero. The limit is shared across all your IRAs, traditional and Roth, so $7,500 is the total for the year, not per account. The test is Modified Adjusted Gross Income. If you are near a threshold, pre-tax 401(k) deferrals and HSA contributions reduce MAGI and can restore eligibility.
Backdoor Roth for high earners
Above the phase-out you can still get a Bitcoin ETF into a Roth through a conversion:
- Contribute up to the annual limit ($7,500 for 2026 and 2027) to a traditional IRA without taking a deduction.
- Convert it to a Roth IRA shortly after, before meaningful gains accrue.
- Buy the Bitcoin ETF inside the Roth.
The pro-rata rule applies: if you hold other pre-tax IRA balances, the conversion is partly taxable in proportion to them. To keep a backdoor clean, roll existing pre-tax IRA money into an employer 401(k) first, where the plan allows it.
Withdrawal rules
Contributions come out at any time, at any age, tax-free. You can always take back what you put in. Earnings are tax-free once you are 59½ or older and the five-year condition is met, and otherwise taxable plus a 10% additional tax unless an exception applies.
The 5-year rule is one clock per taxpayer, not one per account. Publication 590-B defines a qualified distribution as one "made after the 5-year period beginning with the first tax year for which a contribution was made to a Roth IRA set up for your benefit." An account opened in 2026 by someone whose first Roth contribution was in 2020 inherits that clock and does not start a new one, so opening a second Roth at another broker costs nothing in waiting time.
Conversions are the exception. Publication 590-B: "A separate 5-year period applies to each conversion and rollover" for purposes of the 10% additional tax on early distributions, and that clock is "not necessarily the same as the 5-year period used for determining whether a distribution is a qualified distribution."
Strategy considerations
Which account should hold the bitcoin sleeve
The sound argument for putting bitcoin in the Roth is asset location: the shelter is worth most on the asset you expect to grow most. Two arguments often used alongside it are simply wrong. A spot Bitcoin ETF pays no dividends, so there is no annual dividend drag to escape in taxable — the tax arrives only at sale. And Bitcoin ETF shares held in a taxable account do get a basis step-up at death, like any inherited security; Publication 551: "Generally, the basis of property inherited from a decedent is… the FMV of the property at the date of the individual's death." It is IRA assets, Roth included, that never get one. If anything, the step-up argues for leaving the most appreciated positions in taxable and bequeathing them.
Don't time-bet inside the Roth
The Roth shelters gains, and in exchange it discards losses: sell inside it at a loss and there is nothing to deduct. DCA and hold is the cleanest approach. Harvesting belongs in taxable accounts only; see tax-loss harvesting a Bitcoin ETF.
Roth conversion ladder for early retirement
Early retirees can convert traditional IRA balances to Roth in low-income years, moving bitcoin exposure across gradually. Each conversion starts its own five-year clock for the early-distribution tax, so a ladder has to be built years ahead of the money being needed.
Common mistakes
- Contributing above the income phase-out. Excess contributions carry a 6% excise tax, which Publication 590-A says you avoid only if the excess is withdrawn by the due date of the return, including extensions.
- Misreading the 5-year clock in either direction: a new account does not restart it if you already had a Roth, and it does not shorten it if you never did.
- Paying a 1.50% fee by default because the first ticker that came up was GBTC. Compare the fee table above.
- Buying a futures-based fund such as BITO by mistake, covered in spot vs futures Bitcoin ETF.
- Putting the entire Roth into bitcoin without deciding to. Fine if intentional; check it against the rest of the portfolio.
FAQ
Can I hold a Bitcoin ETF in a Roth IRA?
Yes. Every major US brokerage supports spot Bitcoin ETFs (IBIT, FBTC, ARKB, EZBC, BITB, HODL and others) in Roth IRA accounts. Vanguard, which refused to carry the category until December 2025, now allows trading of select third-party cryptocurrency ETFs on its brokerage platform as well.
What are the Roth IRA contribution limits for 2026 and 2027?
$7,500 a year in both years, or $8,600 if you are 50 or older (the catch-up is $1,100). The income phase-out for 2026 runs from $153,000 to $168,000 of modified AGI for single filers and from $242,000 to $252,000 for married couples filing jointly. For 2027 the IRS raised it to $158,000 to $173,000 and $250,000 to $260,000. 2026 contributions can be made until 15 April 2027.
Can I buy a Bitcoin ETF in a Roth IRA if I earn over the income limit?
Not directly, but a backdoor Roth works: contribute to a non-deductible traditional IRA, then convert to Roth shortly after. The conversion is tax-free only if you have no other pre-tax IRA balances, because of the pro-rata rule. Inside the converted Roth you can buy any spot Bitcoin ETF.
Does opening a new Roth IRA restart the 5-year clock?
No. The five-year period begins with the first tax year for which you contributed to any Roth IRA set up for your benefit, not with each account. A Roth opened in 2026 by someone whose first Roth contribution was in 2020 is already past it. Conversions are separate: each has its own five-year period for the 10% early-distribution tax.
Which Bitcoin ETF is cheapest to hold in a Roth IRA?
As of 17 November 2026, the lowest sponsor fees among US spot Bitcoin ETFs were Morgan Stanley MSBT at 0.14% and Grayscale Bitcoin Mini Trust (BTC) at 0.15%, followed by Franklin EZBC at 0.19%. IBIT and FBTC, the two largest funds, charge 0.25%; GBTC charges 1.50%. Fees change, so check the current figure before buying.
Is a Roth IRA better than a taxable account for Bitcoin ETFs?
For a long-term hold you intend to spend, almost always: the Roth shelters all gains, while a taxable liquidation costs 20% long-term capital gains plus the 3.8% NIIT. The case that favours taxable is inheritance — shares in a taxable account get a basis step-up to fair market value at death, which IRA assets never get.
Sources and further reading
- IRS Publication 590-A, "Contributions to Individual Retirement Arrangements (IRAs)", What's New for 2026, irs.gov.
- IRS Publication 590-B, "Distributions from Individual Retirement Arrangements (IRAs)", What Are Qualified Distributions, irs.gov.
- IRS Publication 551, "Basis of Assets", Inherited Property, irs.gov.
- IRS, "COLA increases for dollar limitations on benefits and contributions", 2026 column, irs.gov.
- IRS news release IR-2026-136, "401(k) limit increases to $25,500 for 2027, IRA limit remains $7,500", 12 November 2026, and Notice 2026-66, irs.gov.
- cryptoetf.today fund data, 17 November 2026: sponsor fees and net assets of US spot Bitcoin ETFs.
- Internal: Bitcoin ETF in a 401(k), Tax-loss harvesting, Bitcoin ETF tax in the USA.
For information only. Not investment advice.

 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC