A 9-point checklist for picking the right Bitcoin ETF — fee, custody, liquidity, tracking, broker access. Use it once and pick one fund.
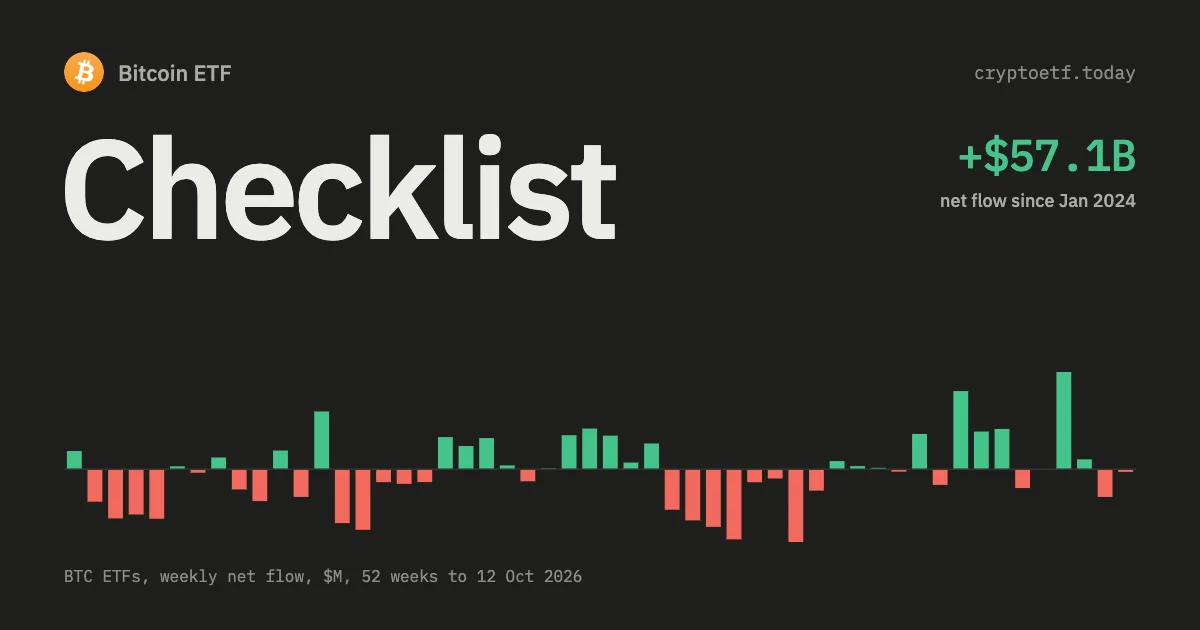
TL;DR. The US spot Bitcoin ETF field is bigger than the January 2024 debut cohort. Twelve funds sit in our tracker, and Osprey's OBTC listed on Nasdaq on 19 December 2025 as a thirteenth. In practice you are choosing between five or six funds that work almost the same way. Run this checklist once. For the average buy-and-hold investor the answer is IBIT or FBTC; the checklist is there to catch the cases where another fund fits better.

Bitcoin ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 5 sections
The checklist
1. Account type
Roth IRA or 401(k) → the tax wrapper already does most of the work, so pick on liquidity and convenience. Taxable account → the fee compounds directly against you, and switching later means realising a gain, so give cost more weight up front.
2. Holding period
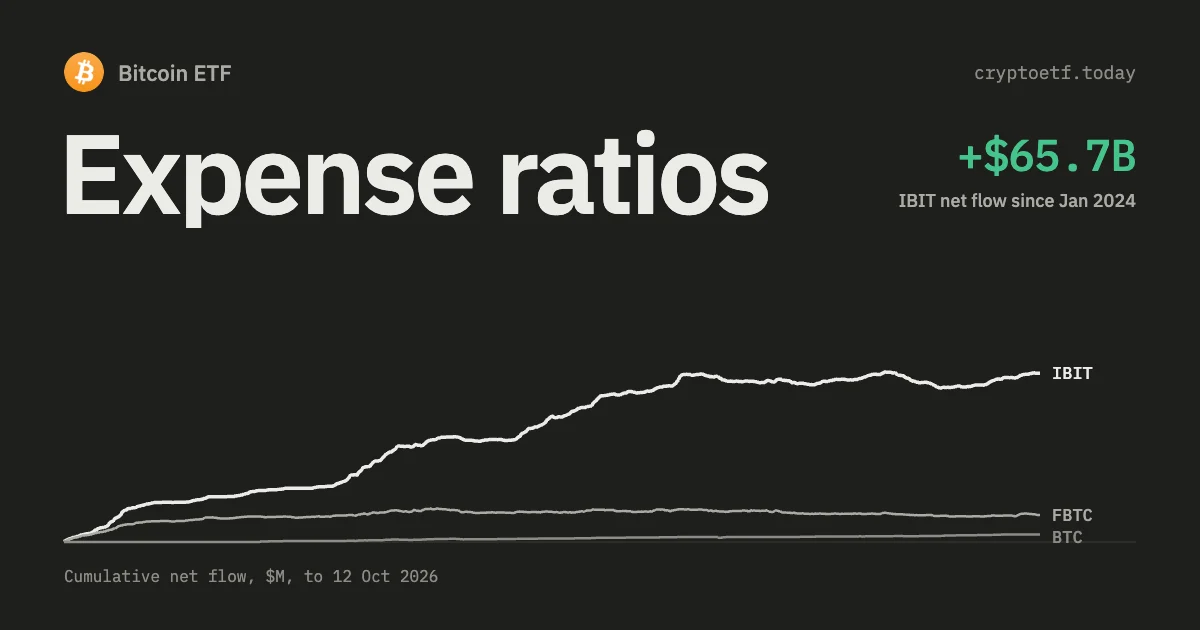
Buy and hold for five years or more → the fee dominates. The cheapest listed funds are MSBT at 0.14% (Morgan Stanley, listed 8 April 2026), the Grayscale Bitcoin Mini Trust at 0.15%, EZBC at 0.19%, and HODL and BITB at 0.20%. If you trade or hold for shorter periods, the spread matters more than the fee, and that points to IBIT.
3. Position size
Under $50k → fee differences are small in dollars, so decide on something else. $50k–$500k → a few basis points start to add up to real money. $500k+ → the bid-ask spread on entry and exit can cost more than a year of fee difference, so liquidity comes before cost.
4. Custody
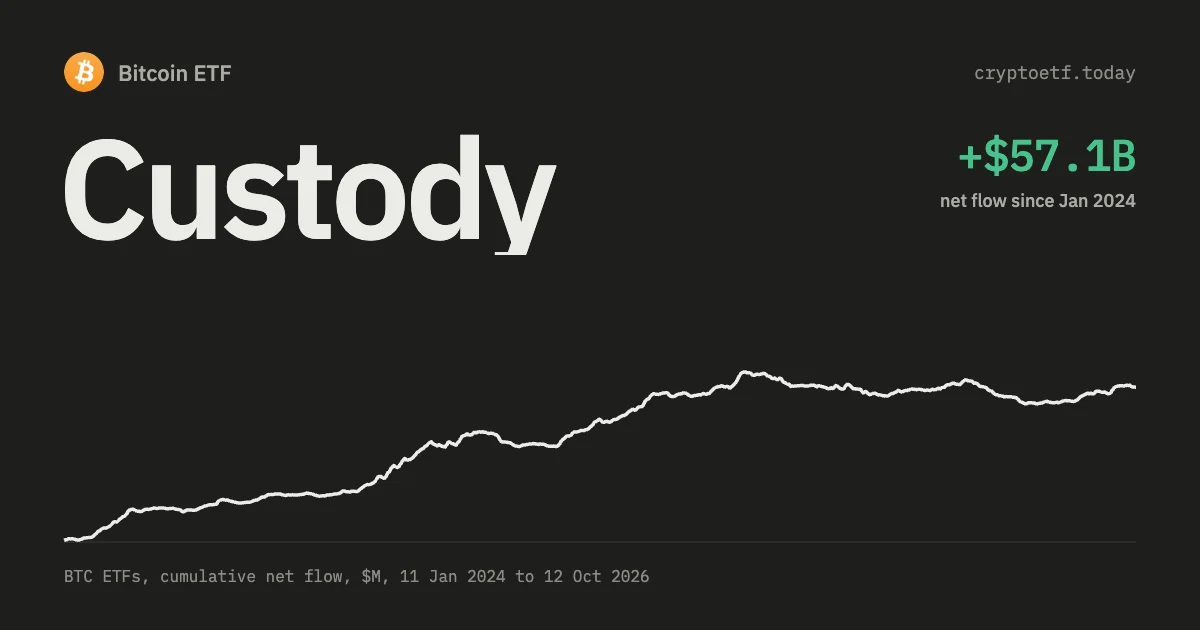
The single-custodian picture people remember from 2024 is out of date. IBIT, GBTC and the Grayscale Mini Trust use Coinbase Custody and Anchorage Digital Bank. HODL uses Gemini and Coinbase. ARKB spreads its coins across four: Coinbase Custody, BitGo Bank & Trust, BitGo New York Trust and Anchorage. FBTC is the only fund with no Coinbase exposure at all: Fidelity holds the coins itself, through Fidelity Digital Assets. If you worry about concentration at one custodian, FBTC removes it, and a multi-custodian fund such as ARKB reduces it.
5. Broker availability
This used to be a real filter. It no longer is. Vanguard, the last holdout, began allowing select third-party crypto ETFs on its brokerage platform in December 2025. Some smaller brokers still restrict the smallest funds, so check your broker's list before you decide.
6. Tracking quality
Look up each issuer's most recent 30-day average premium and discount and prefer the tighter one. IBIT and FBTC are consistently near the top, as you would expect from the two deepest books. Nobody publishes an industry threshold for "fine" versus "worrying", so the useful comparison is fund against fund. More in Bitcoin ETF premium and discount.
7. Liquidity
If you will trade in chunks above $50k, check average daily volume before you choose. IBIT trades an order of magnitude more than the rest of the field, and FBTC is a distant second. The smaller funds have wider spreads, and on a big trade the spread can cost more than the fee they save. Volume changes from month to month, so pull current figures from your broker; any published snapshot goes stale.
8. Issuer relationship
Existing iShares investor → IBIT. Existing Fidelity client → FBTC. Existing 21Shares, Bitwise or VanEck client → ARKB, BITB or HODL. Keeping to one fund family saves you a tax-reporting line and a platform login. Over a decade that is worth more than it sounds.
9. Open-source funding (optional)
Two issuers pledged part of their fund profits to bitcoin protocol development. The common claim that BITB is alone in this is wrong. BITB has the larger pledge: Bitwise committed "10% of BITB profits" to Brink, OpenSats and the Human Rights Foundation's Bitcoin Development Fund, and has since published two annual payments, $150,000 in February 2025 and $233,000 in March 2026. HODL is the other. VanEck said at launch that it "intends to donate 5% of its profits from HODL to the non-profit Brink… for at least 10 years", in a free writing prospectus filed with the SEC on 11 January 2024.
Treat both as marketing commitments. Neither is a fund obligation: neither appears in a prospectus or a 10-K, and VanEck's pledge is no longer mentioned anywhere on its own HODL pages. Bitwise is the one with a published record of actually paying.
The default answer
For most investors the checklist lands on IBIT. It has the deepest liquidity and the broadest broker support, it tracks tightly, and it works in every account type. The exceptions:
- You want custody outside Coinbase entirely → FBTC.
- You are optimising cost over a very long hold → MSBT, the Grayscale Mini Trust or EZBC.
- An existing relationship pulls you elsewhere → ARKB, BITB, BTCO and the rest.
- You hold legacy GBTC with embedded gains → the switch may cost more in tax than you would save on the 1.50% fee.
The quick-reference table
| If you… | Pick |
|---|---|
| Want the safest default | IBIT |
| Want no Coinbase exposure | FBTC |
| Want the lowest fee listed | MSBT (0.14%) |
| Optimise fee with a longer track record | Grayscale Mini Trust (0.15%) or EZBC (0.19%) |
| Want multiple custodians inside one fund | ARKB |
| Want to fund Bitcoin development | BITB (10% of profits) or HODL (5%) |
| Are an existing Fidelity client | FBTC |
| Hold GBTC with embedded gains | Run the tax arithmetic before switching |
| Want custody diversification across funds | Split IBIT + FBTC |
FAQ
Which Bitcoin ETF is best for most investors?
IBIT, the iShares Bitcoin Trust ETF, is the safe default for a buy-and-hold investor. It has the deepest liquidity, tracks tightly, is available at every major broker, and its 0.25% fee is in the middle of the field. If you have no particular view on custody or cost, this is usually where you end up.
Should I split bitcoin exposure across multiple ETFs?
Custody diversification is the one reason that holds up, and it works in only one combination: IBIT plus FBTC, because Fidelity is the only issuer that does not use Coinbase at all. Splitting between funds that share a custodian doubles the paperwork and diversifies nothing.
Is a few basis points of fee difference worth chasing?
On a $100,000 position the gap between IBIT at 0.25% and EZBC at 0.19% is about $60 a year; against MSBT at 0.14% it is about $110 a year. Over a decade that is real money but not decisive, and if you trade in size, a wider bid-ask spread on a thinner fund can wipe it out. For long holds of modest amounts, the cheaper fund wins.
How important is the Bitcoin ETF issuer brand?
For pure economic exposure, hardly at all: the funds hold real bitcoin under similar structures and regulatory frameworks. The brand matters in other ways. It decides how much you trust the operator during a stress event, whether you can consolidate with accounts you already have, and, indirectly, liquidity, because the biggest names attract the deepest books.
Which Bitcoin ETF donates to open-source development?
Two do. Bitwise pledged 10% of BITB profits to Brink, OpenSats and the Human Rights Foundation's Bitcoin Development Fund, and has published two annual donations: $150,000 in February 2025 and $233,000 in March 2026. VanEck pledged 5% of HODL profits to Brink for at least ten years, in a free writing prospectus filed with the SEC in January 2024. Neither pledge is written into a prospectus or a 10-K, so neither fund is bound by it.
Can I switch Bitcoin ETFs later if my situation changes?
In a Roth IRA or any tax-advantaged account, yes, freely and with no tax consequence. In a taxable account a switch is a sale that realises the embedded gain, so for a long-held appreciated position the tax bill usually outweighs any fee saving.
Sources and further reading
- Bitwise, "Funding Bitcoin" and its 2025 and 2026 donation announcements: bitbetf.com, bitwiseinvestments.com.
- VanEck Bitcoin Trust free writing prospectus filed under Rule 433, 11 January 2024 (sec.gov).
- Internal: Expense ratios compared, How Bitcoin ETF custody works, Premium and discount.
For information only. Not investment advice.
 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC