A plumbing-level look at how a spot Bitcoin ETF holds its coins — which fund uses which custodian, how many now use two or more, and what "proof of reserves" does not verify.
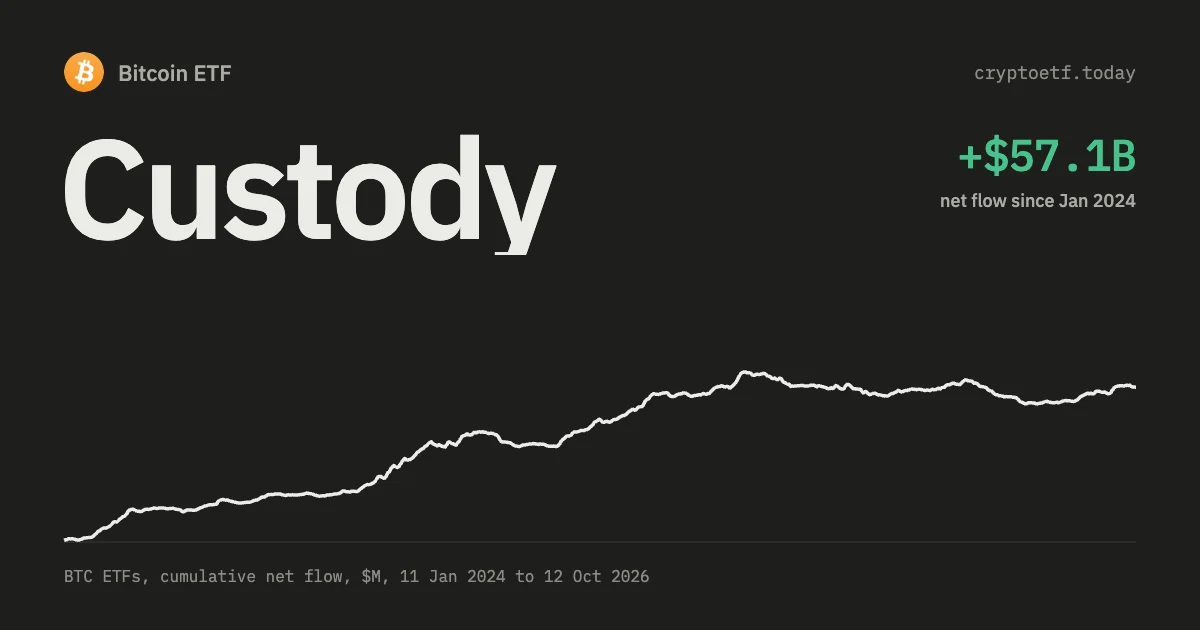
TL;DR. A spot Bitcoin ETF does not hold its own bitcoin. A qualified custodian does, and for most US funds that is Coinbase Custody Trust Company, a New York-chartered trust company. The coins sit in offline (cold) wallets, segregated per fund. Since launch several funds have started naming two or more custodians, so the category leans on one firm less than it did in 2024, although Coinbase still holds the large majority of the assets. The setup is solid. It is still not self-custody, and "proof of reserves" verifies less than its name suggests.

Bitcoin ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 11 sections
- The legal stack: trust, sponsor, custodian
- Who actually custodies US spot Bitcoin ETFs?
- How the coins are actually held
- Insurance: what's actually covered
- Creation and redemption: how coins move in and out
- "Proof of reserves": what it does and doesn't verify
- The real structural risks, in order
- How to verify a fund's custody for yourself
- FAQ
- Bottom line
- Sources and further reading
The legal stack: trust, sponsor, custodian
A spot Bitcoin ETF is set up as a grantor trust under US law. Four roles matter:
- Sponsor. The fund manager (BlackRock, Fidelity, Invesco, Franklin and so on). It markets the product, files with the SEC and earns the fee. It never touches the coins.
- Bitcoin custodian. A regulated entity that holds the bitcoin, controls the private keys and moves coins when the sponsor instructs it to.
- Administrator and cash custodian. Usually BNY Mellon. It calculates NAV, acts as transfer agent and holds any cash, but never bitcoin.
- Authorised participants. Broker-dealers who deliver cash or coin to the trust in exchange for new shares, and take it back when shares are redeemed. BlackRock's filings name Jane Street, Virtu Americas, JP Morgan Securities and Marex Capital Markets as the APs able to settle IBIT in kind; most issuers just write "the Authorized Participants". See our explainer on APs.
The split has a legal purpose. If the sponsor fails, the trust's bitcoin sits in a bankruptcy-remote structure and belongs to shareholders, not to the sponsor's creditors.
Who actually custodies US spot Bitcoin ETFs?
Net assets below are from each fund's Form 10-Q for the quarter ended 30 June 2026.
| ETF | Ticker | Bitcoin custodian(s) | Net assets, 30 Jun 2026 |
|---|---|---|---|
| iShares Bitcoin Trust (BlackRock) | IBIT | Coinbase Custody + Anchorage Digital Bank | $43.39bn |
| Fidelity Wise Origin Bitcoin Fund | FBTC | Fidelity Digital Assets | $10.30bn |
| Grayscale Bitcoin Trust | GBTC | Coinbase Custody + Anchorage Digital Bank | $8.14bn |
| Grayscale Bitcoin Mini Trust | BTC | Coinbase Custody + Anchorage Digital Bank | $3.19bn |
| Bitwise Bitcoin ETF | BITB | Coinbase Custody | $2.13bn |
| ARK 21Shares Bitcoin ETF | ARKB | Coinbase Custody, BitGo Bank & Trust, BitGo New York Trust, Anchorage | $1.89bn |
| VanEck Bitcoin ETF | HODL | Gemini Trust Company + Coinbase Custody | $0.96bn |
| CoinShares Bitcoin ETF | BRRR | Coinbase Custody, BitGo Trust Company, Komainu (Jersey) | $0.34bn |
| Franklin Bitcoin ETF | EZBC | Coinbase Custody | $0.33bn |
| Invesco Galaxy Bitcoin ETF | BTCO | Coinbase Custody | $0.32bn |
| WisdomTree Bitcoin Fund | BTCW | Coinbase Custody | $0.14bn |
The table shows two things. The first is concentration: funds that name Coinbase Custody as a bitcoin custodian account for roughly 85% of the category's $71.42 billion. The second is that fewer funds now depend on Coinbase alone. The 2024 prospectuses described one custodian per fund. Since then IBIT, GBTC and the Grayscale Mini have added Anchorage Digital Bank, ARKB names four entities, HODL names Gemini plus Coinbase, and BRRR names Coinbase, BitGo Trust Company and Komainu (Jersey) Limited. FBTC is still the only fund custodied entirely outside the third-party market, at Fidelity's own custody entity.
How the coins are actually held
In cold storage, segregated per client.
Cold storage
"Cold" means the private keys live on hardware that never goes online, in physically secured facilities spread across several locations. To move coins, someone has to retrieve the key material, sign the transaction offline and broadcast the signed transaction separately. Prospectuses describe this in general terms. The vault design, quorum sizes and key-ceremony procedures are deliberately kept private, so any article that quotes exact numbers for them is guessing.
Key management
Custodians split signing authority so that no single insider can move funds. The usual tools are an n-of-m multisignature scheme, or threshold signatures (TSS/MPC) and secret-sharing schemes, which do the same job without leaving a multisig footprint on chain.
Segregation
Each fund's bitcoin is held in its own addresses, apart from other clients, from the custodian's own balance sheet and from any commingled pool. The IBIT prospectus, for example, says the trust's coins are held in identifiable bitcoin addresses on the bitcoin blockchain. Where a fund publishes its addresses, anyone with a block explorer can watch the balance change as flows come in. Very little in traditional finance can be checked that directly, in real time.
Insurance: what's actually covered
Bitcoin ETF custody and insurance get confused because two different things go by the same name:
- The custodian's commercial crime or specie policy. It covers loss of bitcoin through theft, malicious insiders, physical destruction of key material or computer fraud. The custodian arranges it, not the fund, and custodians generally do not publish the limits in full. Be suspicious of any specific dollar figure unless it comes from the custodian's own disclosure.
- SIPC and FDIC. Neither covers bitcoin. SIPC protects securities accounts up to $500,000. A bitcoin ETF share is a security in your brokerage account and is covered on that basis; the underlying bitcoin is not. Crypto has no FDIC equivalent.
What insurance does not cover:
- A drop in bitcoin's price.
- A fork or chain split where the custodian does not claim the forked coins.
- The sponsor going bankrupt. The trust structure deals with that, not insurance.
- Losses above the policy cap. Any commercial crime policy is small next to $43.39bn of IBIT net assets. The insurance pays out on operational theft up to a limit; it does not guarantee the asset.
Creation and redemption: how coins move in and out
At launch the SEC required the January 2024 funds to create and redeem in cash. The AP delivers dollars, the trust buys bitcoin through a prime broker, and the custodian sweeps the coins into the trust's segregated addresses. Redemptions run the same way in reverse.
That changed on 29 July 2025, when the SEC issued order 34-103571 permitting in-kind creation and redemption for spot crypto ETPs. Funds have taken it up unevenly. VanEck's HODL states that the proceeds it receives from issuing baskets consist of bitcoin. BlackRock's filings name four APs able to settle IBIT in kind. The Grayscale Mini disclosed amended AP agreements in an 8-K filed 6 February 2026. GBTC's 10-Q for the quarter ended 30 June 2026 still says its AP agreements do not provide for in-kind, so every GBTC order runs as cash. Several smaller funds, Franklin's EZBC among them, describe baskets as issued "in exchange for an amount of bitcoin and/or cash".
With cash, the trust carries execution risk between the order and the fill, and every redemption forces it to sell bitcoin. In-kind removes both.
"Proof of reserves": what it does and doesn't verify
Some custodians publish on-chain proof of reserves. It is useful, and it is oversold. It does show two things:
- Existence. A signed message from an address proves the custodian controls those coins.
- Balance match. If the on-chain balance equals what the trust reports, the assets are there.
It does not show:
- No double-pledging. Nothing on chain stops the same coins being pledged as collateral elsewhere. Proof of reserves is not proof of liabilities.
- Live ownership. A signature today says nothing about whether the keys are compromised tomorrow.
For an ETF this matters less than for an unregulated exchange. The custodian answers to a regulator (the NYDFS for Coinbase Custody Trust and Gemini Trust, a national trust charter for Fidelity's custody entity), and the fund is audited every year. The audit and the regulator do most of the work. Proof of reserves is an extra check on top of them.
The real structural risks, in order
1. Custodian concentration
One custodian behind roughly 85% of category assets is a systemic exposure. Coinbase Custody is a New York trust company, capitalised separately from Coinbase Inc. and bankruptcy-remote. A catastrophic failure there (key compromise, enforcement action, a geopolitical event) would still hit most of the category at once.
This is the risk most worth tracking. It is also why the second-custodian additions of 2025–2026 count for more than they look. IBIT, GBTC and the Grayscale Mini are the three largest Coinbase-custodied funds, and adding Anchorage means none of them now rests on a single custodian.
2. Fork handling
If bitcoin forks and a meaningful second chain appears, as Bitcoin Cash did in 2017, the trust has to decide which side to hold and whether to claim or distribute the forked coins. Prospectuses generally leave that decision to the sponsor. Someone holding their own bitcoin makes that choice; an ETF holder gives it up.
3. Cyber and physical attack on the custodian
Custodians' defences are well developed, but the tail risk is not zero. A successful breach of a major Bitcoin ETF custodian would hit the whole asset class, not one fund.
4. Regulatory action against the custodian
A freeze or enforcement action could lock holdings even with the keys intact. For Bitcoin ETFs this is theoretical so far. Other asset classes have seen it happen.
How to verify a fund's custody for yourself
- Open the fund's latest 10-Q or 10-K, free on EDGAR at sec.gov, and search for "Custodian". The exact legal entities are named, and funds with more than one list them all.
- Check recent 8-K filings for changes to custody or AP arrangements. The Anchorage additions and the in-kind amendments were disclosed there.
- Look up the custodian on its regulator's public register (NYDFS for Coinbase Custody and Gemini Trust).
- For funds that publish custody addresses, paste them into mempool.space and compare the balance with reported holdings.
FAQ
Who holds the bitcoin behind a Bitcoin ETF?
A qualified custodian, most often Coinbase Custody Trust Company. Fidelity FBTC is custodied by Fidelity Digital Assets. VanEck HODL names Gemini Trust Company, with Coinbase Custody as an additional custodian. ARK 21Shares ARKB uses four custodians, including two BitGo entities and Anchorage, and IBIT, GBTC and the Grayscale Mini Trust name Anchorage Digital Bank alongside Coinbase.
How concentrated is Bitcoin ETF custody?
Funds that name Coinbase Custody as a bitcoin custodian accounted for roughly 85% of the category's $71.42 billion at 30 June 2026. At launch almost every fund used Coinbase alone; several of the largest have since added a second custodian. Coinbase is still the biggest single exposure in the category.
Is the bitcoin held by an ETF insured?
The custodian carries commercial crime insurance against theft, insider action and destruction of key material. It does not cover price declines, forks or losses above the policy limit, and those limits are commercial terms that custodians generally do not publish in full. SIPC covers the ETF share in your brokerage account, not the underlying bitcoin. Crypto has no FDIC equivalent.
Do Bitcoin ETFs create and redeem shares in cash or in kind?
Both, now. The January 2024 funds launched cash-only. The SEC permitted in-kind creation and redemption for spot crypto ETPs on 29 July 2025 (order 34-103571). Funds have adopted it unevenly: VanEck HODL receives bitcoin for its baskets and BlackRock names four APs able to settle IBIT in kind, while GBTC's agreements still provide for cash only.
Can I see the bitcoin a fund holds on chain?
In many cases, yes. Funds disclose custody addresses or publish proof-of-reserve attestations, and you can check the balance on any block explorer. What that cannot show you is whether the same coins are pledged elsewhere: proof of reserves is not proof of liabilities.
What happens to my shares if the ETF sponsor goes bankrupt?
The trust structure is bankruptcy-remote, so the bitcoin belongs to shareholders, not to the sponsor. In practice another firm would take over as sponsor, or the trust would be wound down and the proceeds paid out. A custodian failure would do more damage than a sponsor failure.
Bottom line
On custody and security, a Bitcoin ETF is well ahead of retail crypto storage: segregated addresses, offline keys, split signing authority, a regulated custodian and an annual audit. The remaining risk is mostly concentration. One custodian stands behind most of the category, in one jurisdiction, on one chain. That has improved since launch as the largest funds added second custodians, but it has not gone away. If you want real custody diversification, holding some bitcoin yourself is still the strongest hedge available.
Sources and further reading
- Forms 10-Q for the quarter ended 30 June 2026 for IBIT, FBTC, GBTC, the Grayscale Bitcoin Mini Trust, BITB, ARKB, HODL, EZBC, BTCO and BTCW: sec.gov/Archives/edgar.
- SEC order 34-103571, 29 July 2025, permitting in-kind creation and redemption for spot crypto ETPs: sec.gov.
- NYDFS public register of virtual currency business licensees: dfs.ny.gov.
- Internal: Bitcoin ETF vs Spot Bitcoin, Authorised Participants Explained.
For information only. Not investment advice.
 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC