Spread, premium and closing drift measured across all twelve US spot Bitcoin ETFs, the GBTC discount that reached 48.9%, and what to check before you place an order.
TL;DR. A US spot Bitcoin ETF trades within a few basis points of net asset value, and authorised participants are the ones who close the gap. Nothing you can trade does. On 22 September 2026 the eleven funds that publish the figure showed a 30-day median bid/ask spread between 0.02% and 0.07%, against 0.37% to 0.46% at the small altcoin trusts. Where they differ is at the closing bell: measured against IBIT over the twelve months to that date, Fidelity's FBTC sat 0.16% from its usual relationship on a typical day and WisdomTree's BTCW 0.64%, four times as far. GBTC is the extreme case, a closed-end trust that closed at a 48.9% discount on 13 December 2022 and has given up $27.84bn since it became redeemable in January 2024. In practice: use a limit order, skip the opening minutes (five-minute ranges in IBIT run about 2.5 times the midday figure), and read the 30-day spread before anything large.

Bitcoin ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 10 sections
- What NAV, premium and discount actually mean
- Where the numbers live, and which one to trust
- How far the twelve US Bitcoin funds actually drift
- GBTC: the most expensive discount in crypto
- How the arbitrage closes the gap, and why a small fund closes it slower
- What in-kind creation changed
- When the gap actually widens
- What it costs you, and what to do about it
- FAQ
- Sources and further reading
What NAV, premium and discount actually mean
A spot Bitcoin ETF has two prices, built differently. Net asset value is an accounting number struck once per business day: take the bitcoin the trust holds, value it against a reference rate, subtract the accrued sponsor fee, divide by shares outstanding. That reference rate is an average taken over a New York afternoon, not a single exchange print, so NAV stays calm on a violent day. IBIT, for example, prices against the CME CF Bitcoin Reference Rate, New York Variant, over the hour to 4pm Eastern. Market price is whatever somebody last paid on the exchange. It updates from 9:30 to 16:00 Eastern and stops dead outside those hours, while bitcoin keeps trading.
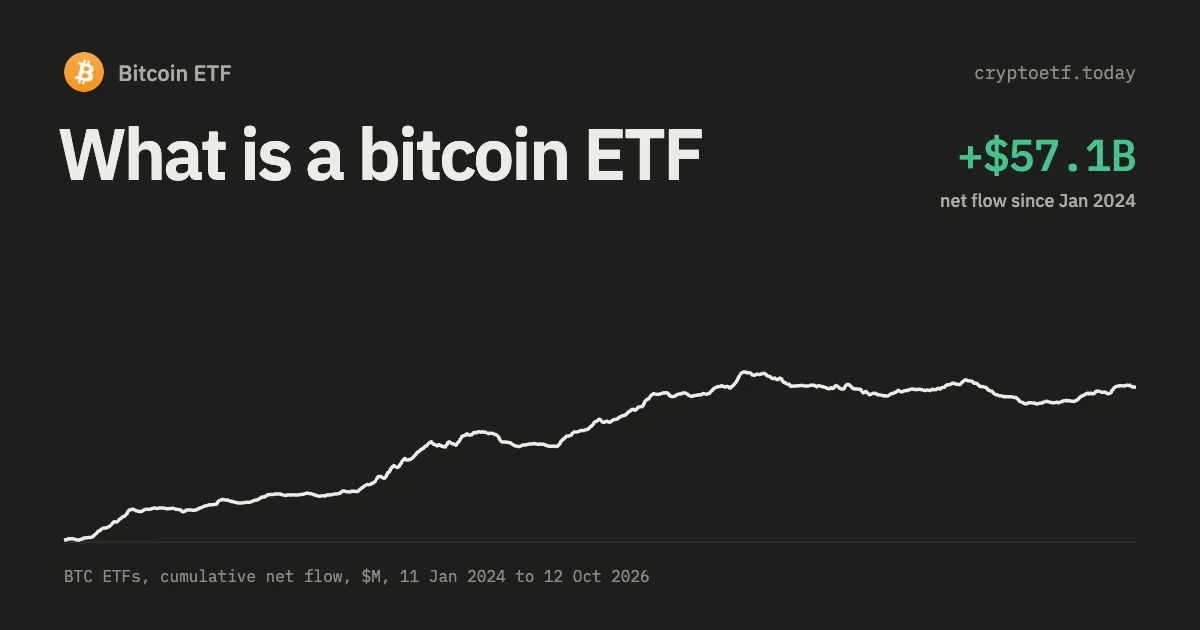
The premium or discount is the difference expressed against NAV: (market price − NAV) ÷ NAV. Above NAV is a premium, below is a discount. On a fund where arbitrage works, it flips sign constantly and one day's figure means nothing. What matters is how big it gets and how long it lasts. If you're new to the wrapper, start with what a Bitcoin ETF actually is.
Where the numbers live, and which one to trust
Every US issuer publishes the same small set of figures on the fund page, with a one-day lag and an as-of date. Some are more useful than others.
- Closing premium or discount: one day's snapshot. It is noisy, it changes sign, and it is the number most often quoted out of context.
- 30-day median bid/ask spread: the best single figure for a buyer. It tells you what a round trip costs right now, and a median doesn't move on one bad afternoon.
- Quarterly premium/discount table: days closed at a premium versus a discount over the last four quarters. This one measures tracking quality and shows which funds wander away from NAV.
One warning before comparing issuers on a single day's premium. On 22 September 2026 five funds published a figure within a hair of each other at −0.20% to −0.21%, while Grayscale published exactly 0.00% and Invesco +0.01%. The funds aren't actually that far apart. They calculate the number differently: some measure the closing price against NAV, others the 4pm bid/ask midpoint, and NAV strike times vary. Compare spreads and quarterly tables instead.
How far the twelve US Bitcoin funds actually drift
Issuer pages give you one fund at a time, on the issuer's chosen date, so we put them side by side and added a measurement of our own. All twelve hold the same asset, so any two should keep an almost constant price ratio, drifting only by the difference in their fees. When a fund's close leaves that ratio, the move is its own pricing noise: a real premium or discount, a wide closing quote, or a stale last print. We took IBIT as the yardstick and measured how far each fund's daily price ratio to it sat from that pair's trailing 20-session median, over the twelve months to 22 September 2026, a window that keeps the Grayscale Mini Trust spin-off of July 2024 out of the sample.
| Fund | Fee | Net assets, issuer page | 30-day median bid/ask spread | Our measured daily dispersion vs IBIT | Widest single close |
|---|---|---|---|---|---|
| IBIT (BlackRock) | 0.25% | $68.34bn | 0.02% | benchmark | — |
| FBTC (Fidelity) | 0.25% | $13.87bn (31 Aug) | 0.04% | 0.16% | 0.81% (30 Jul 2026) |
| GBTC (Grayscale) | 1.50% | $10.97bn | 0.02% | 0.18% | 0.74% (14 Nov 2025) |
| BTC (Grayscale Mini) | 0.15% | $5.42bn | 0.03% | 0.18% | 0.60% (13 Jul 2026) |
| BITB (Bitwise) | 0.20% | $3.32bn (21 Sep) | 0.02% (20 Sep) | 0.23% | 1.18% (1 Jul 2026) |
| ARKB (ARK 21Shares) | 0.21% | $2.66bn (31 Aug) | 0.04% | 0.23% | 1.63% (7 Mar 2026) |
| HODL (VanEck) | 0.20% | $1.27bn | 0.04% | 0.30% | 1.14% (24 Oct 2025) |
| MSBT (Morgan Stanley) | 0.14% | $759m (see note) | 0.04% | 0.60% | 4.50% (28 May 2026) |
| EZBC (Franklin) | 0.19% | $479m | not published | 0.55% | 2.16% (5 Feb 2026) |
| BTCO (Invesco Galaxy) | 0.25% | $440m | 0.07% | 0.58% | 2.57% (5 Feb 2026) |
| BRRR (CoinShares) | 0.25% | $437m (17 Sep) | 0.05% (17 Sep) | 0.61% | 3.15% (5 Feb 2026) |
| BTCW (WisdomTree) | 0.25% | $182m | 0.06% | 0.64% | 3.03% (7 Apr 2026) |
Fees, net assets and spreads come from each issuer's own fund page on 22 September 2026 unless the cell says otherwise. Dispersion and widest-close figures are our own calculation from daily closing prices, 1 September 2025 to 22 September 2026, roughly 270 sessions per fund and 96 for MSBT, which listed on 8 April 2026. Morgan Stanley's page contradicts itself on that date, reporting $758.94m of net assets beside a holdings line worth about $858m, so treat its AUM as unconfirmed.
Compare the last two columns. They differ by an order of magnitude, and both are correct. Eleven of the twelve quote a 30-day median spread between 0.02% and 0.07% (Franklin doesn't publish one), so by that measure spot Bitcoin ETFs trade very tightly: the widest, BTCO at 0.07%, is three and a half times the tightest, and the whole range sits five to twenty times inside the small altcoin trusts, where Canary's LTCC publishes 0.46%, its Hedera fund HBR 0.39% and its Sui fund SUIS 0.37%. Yet our closing-price dispersion runs 0.16% at FBTC and 0.64% at BTCW, a four-to-one gap that tracks assets closely and ignores fees completely.
The difference between the two is the useful part. A quoted spread is what a market maker shows while it is quoting. Dispersion is where the day's last trade actually printed, so it also picks up stale prices and the mismatch between a 4pm close and a NAV strike. In a fund that trades all day the two nearly coincide, and in one that doesn't they can't: across 206 sessions to 22 September 2026 BTCW printed a trade in only 28.1% of the 78 five-minute windows in a session, against 100% for IBIT and 99.1% for GBTC. A tight quote is little use if nobody trades against it.
The issuers' quarterly tables agree. IBIT closed 2025 at a premium on 121 days and a discount on 124, about as even as a coin flip, which is what good tracking looks like. ARKB's third quarter of 2026 ran 36 premium days to 20 discount days, widest premium 0.42% on 3 September, widest discount 0.71% on 29 July, with 98.28% of days inside half a percent of NAV. GBTC's 1.50% fee does not make it harder to trade. At 0.02% its spread ties IBIT's and beats the Mini Trust's, because the fee comes out of NAV and never shows up in the quote.
The practical upshot: paying 0.6% to enter a $182m fund to save six basis points a year is a bad trade unless you'll hold for a decade. Fees and assets fund by fund are in the full directory of US spot Bitcoin ETFs, with up-to-date pages on our funds directory.
GBTC: the most expensive discount in crypto
Everything above describes funds where the arbitrage works. Grayscale's trust shows what happens when it doesn't, and it is the reason most people have heard of ETF discounts at all. The Bitcoin Investment Trust launched in 2013 and began trading on OTCQX in 2015, with shares created through private placements to accredited investors who could resell publicly after a lockup. What the structure never had was redemption: you couldn't hand shares back and receive bitcoin. Creation worked in one direction only.
That asymmetry produced both extremes. When brokerage demand outran the slow, gated supply of new shares, GBTC traded above the value of its coins, and buying at NAV in a placement to sell at a premium six months later became a crowded trade at several large crypto lenders. When demand reversed in 2022 nothing could pull the price back up, and the discount widened to 48.9% on 13 December 2022, weeks after FTX failed and Grayscale's sister company Genesis halted withdrawals. A share representing $20 of bitcoin fetched about $10, and the discount stayed below 30% through most of 2022 and the first half of 2023.
Nothing about bitcoin caused that. The trust held the coins throughout and its NAV tracked bitcoin normally. The 48.9% came entirely from the missing redemption mechanism. That is the main point of this article: a premium or discount tells you about the wrapper. It tells you nothing about bitcoin.
The discount closed on the calendar of the legal case, narrowing through the second half of 2023 as the DC Circuit's August 2023 ruling made conversion look likely, and reaching single digits by the end of December. On 11 January 2024 GBTC began trading on NYSE Arca as a redeemable ETF and the gap vanished, because that morning an authorised participant could finally buy a discounted share, redeem it for bitcoin and sell the bitcoin.
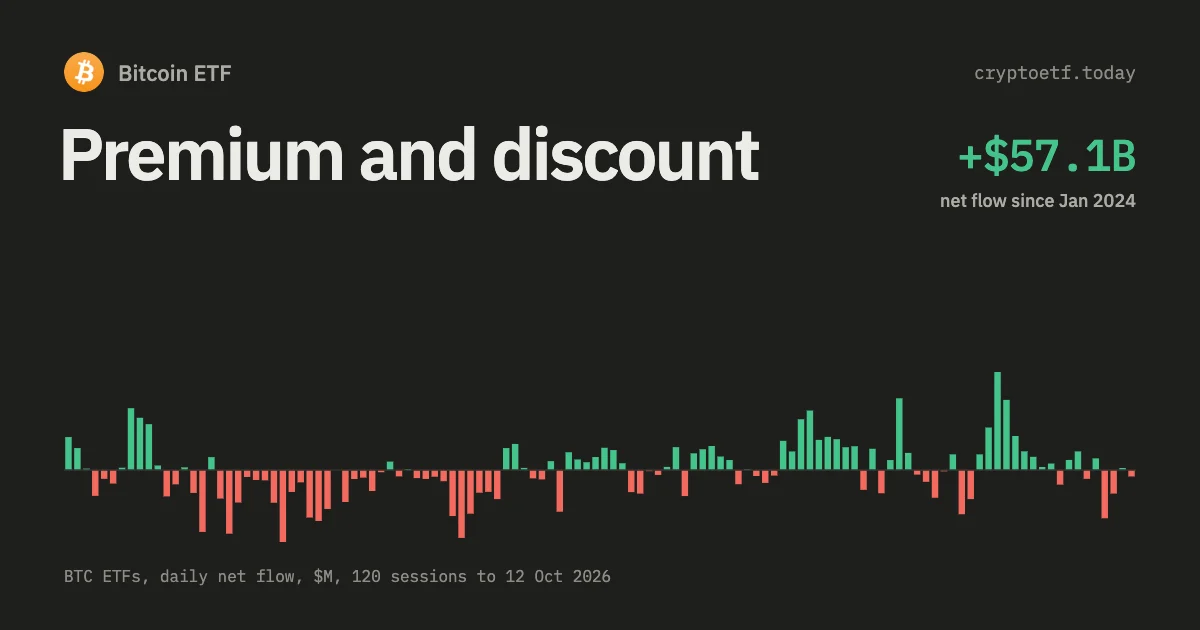
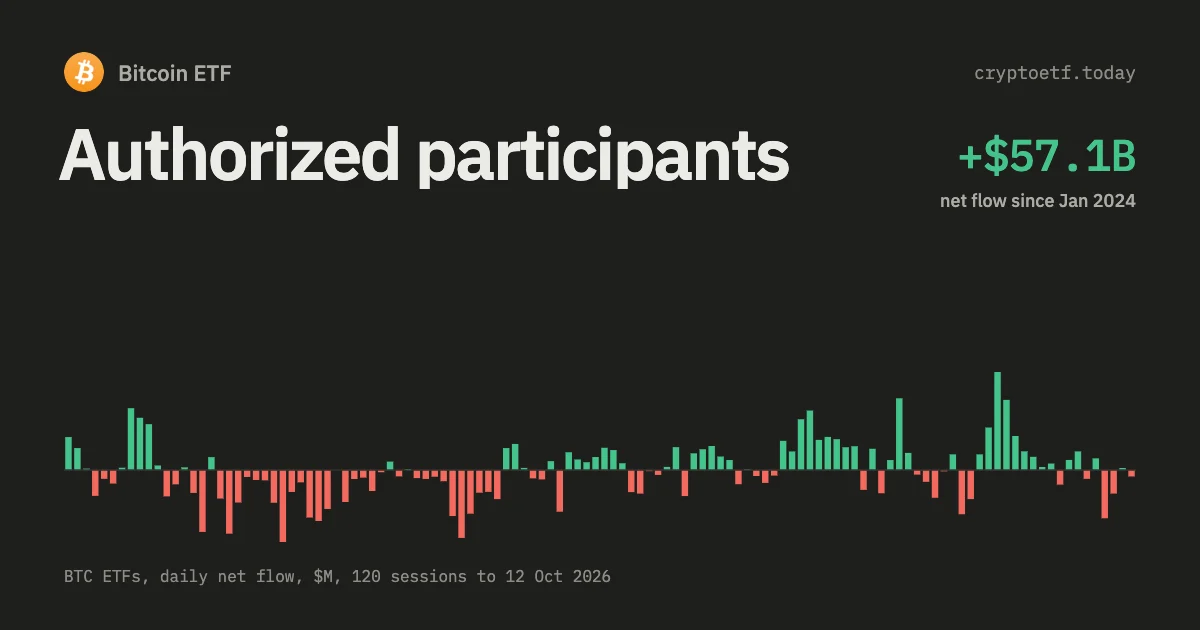
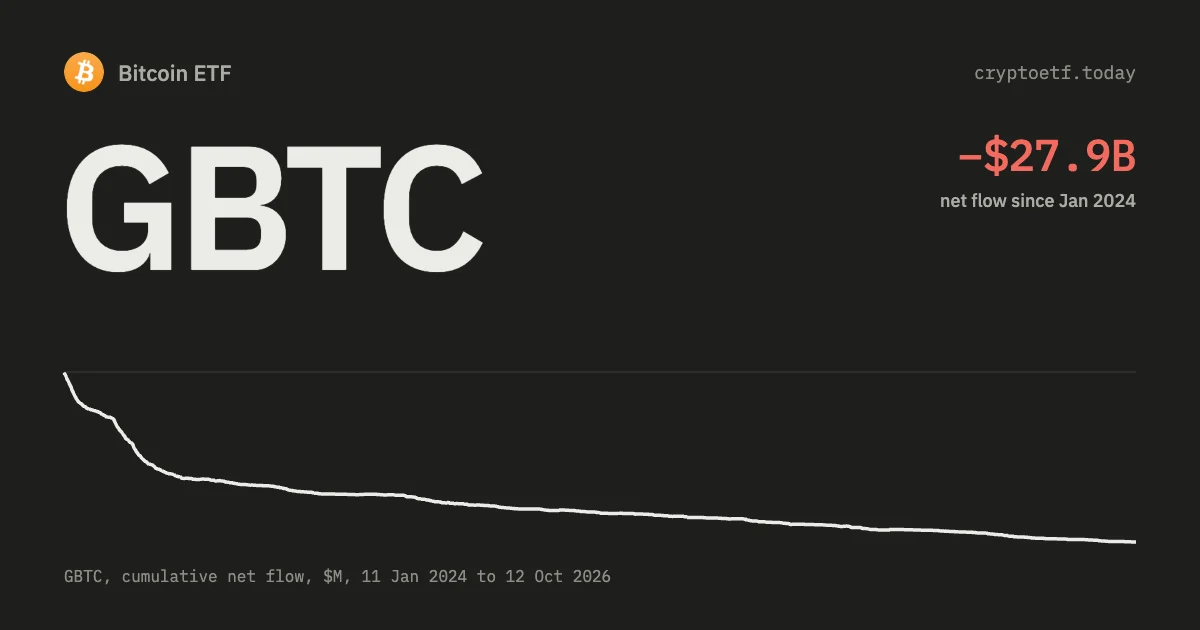
Then the bill arrived. Holders trapped for years could finally leave, and a 1.50% fee gave them a reason to. By our own daily flow data GBTC lost $7.44bn in its first 30 sessions as an ETF, $21.50bn across 2024, and $27.84bn through 22 September 2026, with 181 of 2024's 245 sessions negative and a worst day of $642.5m out on 18 March 2024. Most of that money moved to cheaper funds and stayed in the category, as our Grayscale GBTC analysis shows. Ether went through the same thing: Grayscale's ETHE traded at a reported premium in the hundreds of percent in mid-2020 and near a 59% discount at the end of December 2022.
How the arbitrage closes the gap, and why a small fund closes it slower
Retail buyers never close a premium. Authorised participants do, and only in whole baskets: above NAV an AP delivers bitcoin or cash to the trust, receives new shares and sells them into the premium, and below NAV the trade runs in reverse. Each round trip is riskless in theory but costs real money in practice, and that is why fund size matters. The full walkthrough is in how authorised participants work. Three frictions set the width of the band.
- The basket is indivisible. IBIT's creation unit is 40,000 shares, EZBC's 50,000, and several small funds use 5,000. A 0.3% premium on 40,000 IBIT shares is worth chasing; the same 0.3% on 5,000 shares of a fund that turns over a few hundred thousand dollars a day is worth a few hundred dollars, and the AP still has to unwind into a book that can't absorb it.
- The hedge costs something. Bitcoin moves between the moment an AP quotes and the moment the trust prices the order. Someone pays for that, and the wider bitcoin's realised volatility, the wider the quote.
- Someone has to be trading. This is the friction people underestimate, and it is the 28.1% figure above. In a fund that goes untraded for most of the day, the price on your screen can be an hour old. The gap between that price and NAV is mostly a missing trade, not a premium.
MSBT shows the same thing at launch. Morgan Stanley's fund, at 0.14% the cheapest in the category, printed a close 4.5% away from the rest of the market on 28 May 2026, seven weeks after listing. It might have been a real premium or one thin trade at a bad moment. Either way, a market order could have hit it.
What in-kind creation changed
The 2024 cohort launched cash-only: an AP handed over dollars and the fund itself bought the bitcoin, so the fund's execution slippage ended up inside NAV and the AP had to hedge across the gap. Both of those let the price wander further. On 29 July 2025 the SEC permitted in-kind creations and redemptions for spot crypto ETPs, letting APs deliver and receive the coins directly.
Our dispersion measure across nine funds, pooled by day, moved in the expected direction: the median session ran 0.326% from September 2024 to 28 July 2025 and 0.244% afterwards, a tightening of about a quarter.
| Period | Sessions | Median daily dispersion (9 funds vs IBIT) | Median absolute daily bitcoin move |
|---|---|---|---|
| Sep 2024 to 28 Jul 2025 (cash only) | 225 | 0.326% | 1.64% |
| 29 Jul 2025 to 22 Sep 2026 (in-kind permitted) | 289 | 0.244% | 1.48% |
Our own calculation from daily closing prices and our bitcoin price series. Be careful with the conclusion: bitcoin also got calmer, with the median absolute daily move falling from 1.64% to 1.48%, so some of the tightening has nothing to do with settlement mechanics. Dispersion fell by roughly 25% while volatility fell by roughly 10%, which is consistent with in-kind helping and is not proof of it.
When the gap actually widens
Volatility days
The worst session in our twelve-month window was 5 February 2026, when average dispersion across the ten non-IBIT funds hit 0.96%, four times a normal day's 0.24%, and EZBC, BTCO and BRRR all recorded their widest close of the year on that one date. The next day bitcoin fell 14.7%, from $73,066 to $62,293. The gap widened before the move, not after it, because market makers priced the risk first.
Weekend gaps
Bitcoin trades continuously and the funds don't, so every Monday open absorbs whatever happened since Friday's close. The largest such gap in our series was 6 to 9 February 2026, plus 12.9%, from $62,293 to $70,307 with no session in between; 18 to 21 September gapped 6.5%. A premium printed in the first minutes of a session like that is a stale reference point, and it resolves as soon as real size trades.
The first minutes of the session
This effect can be measured, and avoiding it saves real money. In five-minute candles across recent sessions, the high-to-low range inside each candle decays steadily through the day.
| Minutes after the 9:30 ET open | IBIT median 5-min range | GBTC median 5-min range |
|---|---|---|
| 0 to 5 | 0.42% | 0.37% |
| 5 to 15 | 0.47% | 0.31% |
| 15 to 30 | 0.36% | 0.30% |
| 30 to 60 | 0.31% | 0.24% |
| 60 to 330 (mid-session) | 0.20% | 0.14% |
| 330 to 385 (final hour) | 0.16% | 0.11% |
Our own calculation from five-minute candles: IBIT over 26 sessions to 22 September 2026, GBTC over 42. In both, the opening quarter hour runs roughly two and a half times as wide as mid-session, and the quietest stretch is the final hour, not the first. People are often told to avoid the close too. For the large funds the data says otherwise, and late in the day has an advantage: NAV is struck in the New York afternoon, so a trade near the close is priced against a reference rate already being set. A thin fund is different, because a stale book prints in the closing auction.
The first weeks of a new listing
A new fund has few APs, no float and no natural two-sided flow. MSBT's first fifteen sessions from 8 April 2026 ran about 0.25% above where the rest of the market implied, peaking at 0.65%, and Morgan Stanley's own table shows the same skew over a longer run: since inception the fund has closed at a premium on 82 days against a discount on 26. A mature fund's premium keeps changing sign. MSBT's mostly pointed one way, which is a reason not to rush into a new listing.
What it costs you, and what to do about it
Buy at a 0.3% premium and sell at a 0.3% discount and you've paid 0.6% in slippage, which on a 0.25% fund is more than two years of management fee surrendered on two trades. Over five years the fee dominates and slippage rounds away; on a position you rebalance quarterly it's the larger cost, and nobody quotes it to you. That's why we compare total cost of ownership, and not only the headline fee, in Bitcoin ETF expense ratios compared. Four rules cover almost all of it.
- Always use a limit order. A market order is an instruction to accept whatever the widest quote in the book happens to be. In the tight funds that costs a few basis points; in a $182m fund it can cost more than a year of fees.
- Don't trade in the first fifteen minutes. The table above is the argument. Let the overnight bitcoin move get priced first.
- Check the 30-day median spread, not yesterday's premium. On a Bitcoin fund anything above 0.07% is an outlier; on a small altcoin trust the same figure runs 0.4%.
- Below about $1bn in assets, size matters more than fee. Six basis points saved is roughly $6 a year per $10,000; half a percent of entry slippage is $50, once, up front.
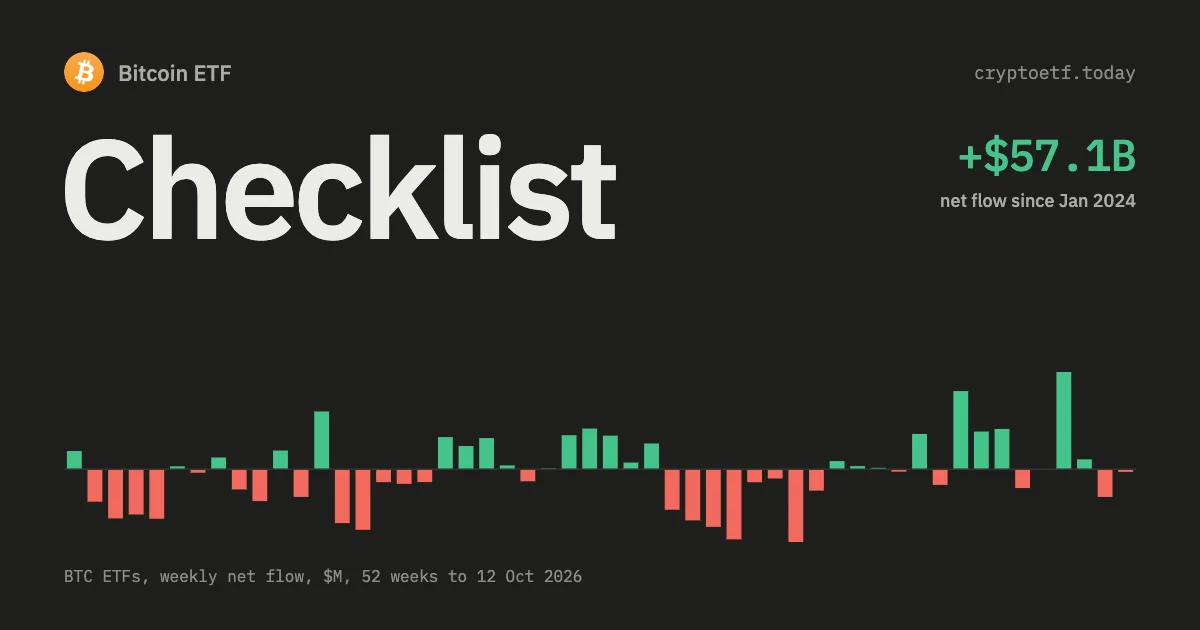
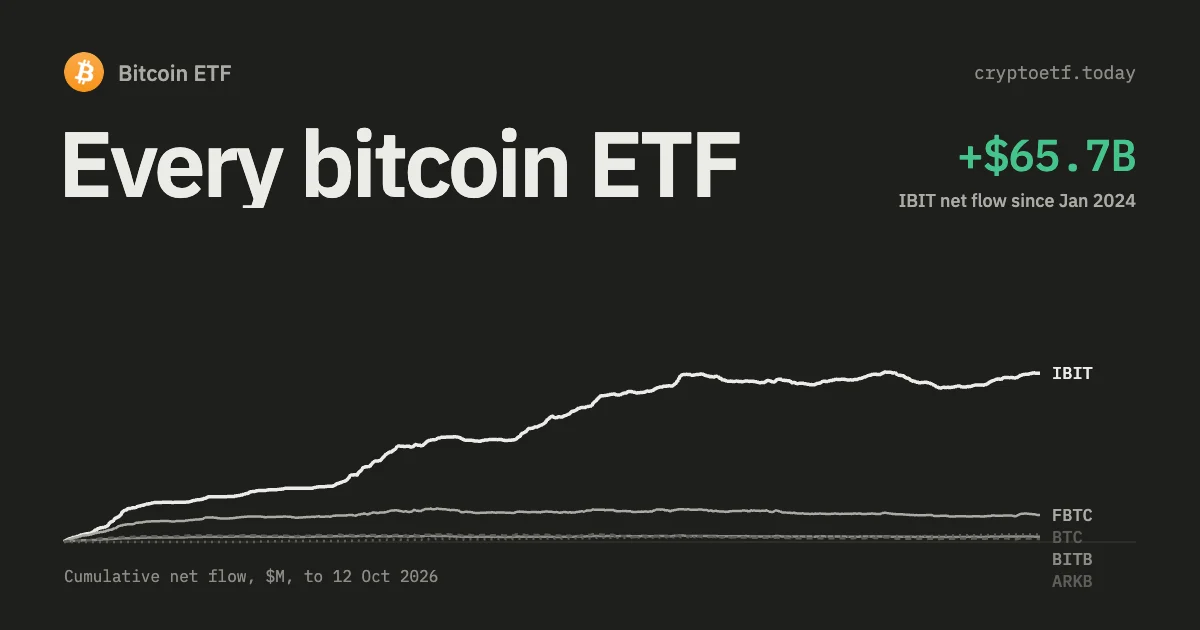
Order mechanics broker by broker are in how to buy a Bitcoin ETF, and the wider screen we run before choosing a fund is the selection checklist. The one signal worth acting on is a persistent, one-directional premium across weeks, because it means creation isn't keeping up. The fastest way to check is our Bitcoin ETF flows page, which shows the daily change in shares outstanding at each fund.
Strip the noise out and a spot Bitcoin ETF returns bitcoin's spot return minus the sponsor fee, give or take a few basis points of friction, Futures-based products don't manage that: their roll costs have nothing to do with the fee and have missed bitcoin by percentage points, as spot versus futures Bitcoin ETFs sets out. A small premium or discount is normal and corrects itself. A persistent one says that a particular fund is thinly traded. A huge one means redemption is broken. Only the third case is a reason to worry, and no US spot Bitcoin ETF has been in it since January 2024.
FAQ
What is a Bitcoin ETF premium or discount to NAV?
It's the difference between the ETF's market price and its net asset value, the accounting value of the bitcoin behind one share, expressed as a percentage of NAV. Above NAV is a premium, below is a discount. US spot Bitcoin ETFs trade within a few basis points either way, and the number flips sign from day to day.
How big is the premium or discount on a typical spot Bitcoin ETF?
Small. Eleven of the twelve US spot Bitcoin ETFs published a 30-day median bid/ask spread between 0.02% and 0.07% on 22 September 2026. Closing prices wander further: measured against IBIT over the prior twelve months, FBTC deviated about 0.16% on a typical day and the sub-$500m funds 0.55% to 0.64%, with widest single closes of 2% to 4.5%.
Why did GBTC trade at a 50% discount?
Because until January 2024 it was a closed-end trust with no redemption mechanism. Shares could be created in private placements but never handed back for bitcoin, so when demand fell there was no arbitrage to pull the price up. The discount reached 48.9% on 13 December 2022, after FTX collapsed and Genesis halted withdrawals, and it closed only when GBTC converted to a redeemable ETF on 11 January 2024.
What happened to GBTC after the discount closed?
Holders locked in for years could finally exit, and the 1.50% fee gave them a reason to. By our own daily flow data GBTC lost $7.44bn in its first 30 sessions as an ETF and $27.84bn through 22 September 2026, with 181 of 2024's 245 sessions negative. Most of that money moved into cheaper funds and stayed in the category.
How do I check the premium or discount before I buy?
Go to the issuer's fund page. Every US issuer publishes the closing price, end-of-day NAV, the premium or discount, a 30-day median bid/ask spread and a quarterly table of days closed at a premium versus a discount. Use the spread and the quarterly table. A single day's closing premium is noise, and issuers don't even calculate it the same way.
Does the premium or discount eat into my returns?
On a multi-year hold the spread averages out and the sponsor fee dominates. On anything you rebalance often it is the larger cost: buying at a 0.3% premium and selling at a 0.3% discount costs 0.6%, more than two years of a 0.25% fee. Entry and exit slippage belongs in total cost of ownership alongside the expense ratio.
When is the worst time of day to buy a Bitcoin ETF?
The first fifteen minutes. In five-minute candles across recent sessions, IBIT's median intra-candle range was 0.42% in the opening five minutes and 0.47% over the next ten, against 0.20% mid-session and 0.16% in the final hour, and GBTC shows the same shape. The overnight bitcoin move gets priced in during those minutes, and a market order placed then often fills at a poor price.
Sources and further reading
- iShares Bitcoin Trust ETF (IBIT) fund page: NAV, premium/discount, 30-day median bid/ask spread and the quarterly days-at-premium table.
- Grayscale Bitcoin Trust ETF (GBTC) fund page: daily NAV, market price, premium/discount and spread.
- Bitwise Bitcoin ETF (BITB) fund page: quarterly premium and discount day counts.
- SEC Release No. 34-99306, 10 January 2024, the order granting accelerated approval to list and trade bitcoin-based trust shares, the filing that let GBTC convert.
- Grayscale Bitcoin Trust filings on SEC EDGAR: annual and quarterly reports covering the discount period and the conversion.
- Internal: how authorised participants work, every US spot Bitcoin ETF in one table, Grayscale GBTC analysis, Bitcoin ETF AUM growth analysis.
For information only. Not investment advice.
 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC