A practical walkthrough of buying a Bitcoin ETF — choosing a broker, opening the right account, picking the fund, placing the order, and recording cost basis to stay tax-compliant.
TL;DR. Buying a spot Bitcoin ETF is a five-step process: (1) choose a brokerage that supports it. Fidelity, Schwab, IBKR and Robinhood are the usual choices, and Vanguard allowed crypto ETPs on its platform on 2 December 2025. (2) Open and fund the account in the most tax-efficient wrapper you have: Roth IRA first, then traditional IRA, then taxable. (3) Pick a fund. IBIT leads on size and liquidity; MSBT, the Grayscale Mini Trust and EZBC are cheapest. (4) Place a limit order during US market hours so you control the price. (5) Write down your cost basis right away. First-time buyers skip this most often, and they pay for it at tax time.
Contents · 10 sections

Step 1 — Choose a brokerage
Spot Bitcoin ETFs trade on US exchanges exactly like any equity ETF. You buy them through the same brokerage you use for index funds or stocks. What you need to know is which brokers carry them, and that list has changed.
Fidelity supports all spot Bitcoin ETFs across every account type (taxable, Roth IRA, traditional IRA, SEP-IRA). It also runs its own fund, FBTC, and holds that fund's bitcoin itself. There are no commissions, and you can buy fractional shares. For most investors it is the simplest place to start.
Charles Schwab supports spot Bitcoin ETFs across account types, with zero commissions, the thinkorswim platform for active traders and full IRA support. Schwab has no Bitcoin ETF of its own, so it has no house fund to push, and it offers fractional ETF shares.
Interactive Brokers (IBKR) suits investors who care most about execution: it has smart order routing and accepts international accounts. The Lite tier is commission-free. The Pro tier charges per share, and its routing is generally better for larger orders. Check the current schedule before you assume either way.
Robinhood supports spot Bitcoin ETFs in taxable and Roth IRA accounts. It is built for the phone, charges no commissions and sells fractional shares. It has fewer account types than full-service brokers: no SEP-IRA and no 401(k) administration.
Vanguard refused to carry spot Bitcoin ETFs when they launched in January 2024, the best-known holdout in the industry. It reversed that policy on 2 December 2025 and now allows crypto ETPs on its brokerage platform. It still does not sponsor a fund of its own. If you last checked in 2024 and gave up, check again. See the full breakdown in best brokerage for Bitcoin ETF.
Brokerage comparison
| Broker | Min investment | Bitcoin ETF support | IRA support | Commission |
|---|---|---|---|---|
| Fidelity | $1 (fractional) | Yes — all spot ETFs incl. FBTC | Roth, traditional, SEP, SIMPLE | $0 |
| Charles Schwab | $1 (fractional) | Yes — all spot ETFs | Roth, traditional, SEP, SIMPLE | $0 |
| Interactive Brokers | $1 (fractional) | Yes — all spot ETFs | Roth, traditional, SEP | $0 (Lite) / per-share (Pro) |
| Robinhood | $1 (fractional) | Yes — all spot ETFs | Roth, traditional | $0 |
| E*TRADE | $1 share price (no fractional) | Yes — all spot ETFs | Roth, traditional, SEP | $0 |
Step 2 — Open and fund the account
There are three account types, listed here from most to least tax-efficient for a long-term Bitcoin ETF hold:
- Roth IRA. You contribute after tax, and growth and qualified withdrawals are tax-free for good. If you plan to hold for a long time, this is the account to use. The 2026 limit is $7,500 a year, plus a $1,100 catch-up at 50 or older, for $8,600 (IRS Notice 2025-67). The contribution phases out between $153,000 and $168,000 of MAGI for single filers and between $242,000 and $252,000 for married couples filing jointly. Above the range, use a backdoor Roth conversion. Full mechanics in Bitcoin ETF in a Roth IRA.
- Traditional IRA or 401(k). Contributions go in pre-tax and lower this year's income, but withdrawals in retirement are fully taxed. It compounds better than a taxable account. For an asset you expect to rise a lot, like bitcoin, a Roth is better.
- Taxable brokerage account. There is no contribution limit and you can take money out any time. Each sale is subject to capital gains tax: 0%, 15% or 20% long-term, plus the 3.8% Net Investment Income Tax for high earners. Use it once retirement accounts are full, or when you need the money before retirement age.
Funding: an ACH bank transfer settles in 1–3 business days. Most brokers give you same-day buying power while it clears, taking the settlement risk themselves. To move an existing account from another brokerage, use ACATS. It takes 5–10 business days and is not a taxable event.
Step 3 — Choose which Bitcoin ETF to buy
Eleven US spot Bitcoin ETFs launched together on 11 January 2024; twelve trade today, after Hashdex's DEFI was liquidated in August 2026 and the Grayscale Bitcoin Mini Trust (July 2024) and Morgan Stanley's MSBT (April 2026) were added. All of them hold actual bitcoin, not futures contracts. Futures funds pay to roll their contracts; see Bitcoin ETF vs spot Bitcoin. Net assets below are from each fund's Form 10-Q for the quarter ended 30 June 2026.
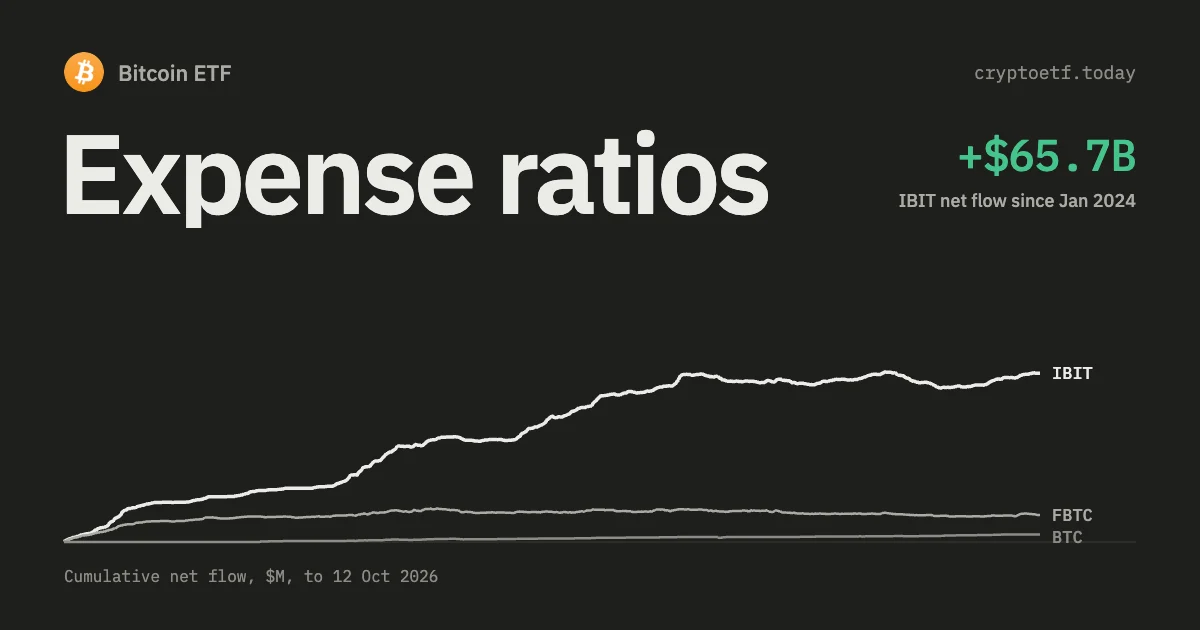
- IBIT (BlackRock iShares): 0.25%, $43.39bn of net assets, more than double the other funds in this list combined. It is the default if liquidity comes first. Custody: Coinbase Custody plus Anchorage Digital Bank.
- FBTC (Fidelity Wise Origin): 0.25%, $10.30bn. The only fund whose bitcoin sits entirely with its sponsor's own custody entity, Fidelity's, so it avoids Coinbase completely.
- BITB (Bitwise): 0.20%, $2.13bn. Custody: Coinbase Custody.
- HODL (VanEck): 0.20%, $0.96bn. The only fund naming Gemini Trust Company as bitcoin custodian. It also names Coinbase Custody as an additional custodian, so custody is split between the two.
- EZBC (Franklin Templeton): 0.19%, $0.33bn. Cheapest of the January 2024 cohort. Custody: Coinbase Custody.
- BTC (Grayscale Bitcoin Mini Trust): 0.15%, $3.19bn. Spun out of GBTC in July 2024. Custody: Coinbase Custody plus Anchorage.
- MSBT (Morgan Stanley): 0.14%, the cheapest in the category. Listed on NYSE Arca on 8 April 2026, so it has the shortest track record.
If you want one default fund, IBIT wins on size and liquidity. Over a multi-decade hold the fee matters most, which points to MSBT, the Grayscale Mini or EZBC. To get away from Coinbase custody, pick FBTC; HODL gets you halfway. The detailed fee math is in Bitcoin ETF expense ratios compared.
Avoid buying multiple Bitcoin ETFs without a plan. Owning IBIT plus FBTC plus ARKB adds no diversification, because all three hold the same asset. It does add paperwork at tax time and a second and third set of fees.
Step 4 — Place the order
Spot Bitcoin ETFs trade on NYSE Arca and Cboe BZX during standard US market hours: 9:30 a.m. to 4:00 p.m. Eastern Time. Many brokers offer extended-hours trading, but spreads are much wider then and fills are worse.
Market order vs limit order
A market order executes immediately at whatever price the market offers. On the largest funds during mid-session hours the spread is narrow enough that a market order is fine. At the open and the close it widens as market makers reprice around overnight bitcoin moves, and in the small funds it is wider all day. You will not see what that cost you, because it is buried in the fill price. That is why a limit order is the safer habit.
A limit order sets the most you will pay. Put the limit at the bid-ask midpoint, or 1–2 cents above the ask if you want an immediate fill with a cap on price. Use one for any order above a few thousand dollars and for anything near the open or close.
Understanding NAV vs market price
Bitcoin ETF NAV (net asset value) is struck once each business day, generally as of 4:00 p.m. Eastern Time, using the fund's bitcoin reference rate. During trading hours the ETF trades at a market price that moves in real time, so it sits at a small premium or discount to the last NAV. In the largest funds that gap is small; in the smallest funds and outside core hours it can be wider. Check the fund's intraday indicative value on your broker's platform before placing a large order, and see premium and discount to NAV for how it behaves.
Fractional shares
Share prices across the twelve funds ranged from about $24 to $89 at the close on 23 September 2026. The difference comes from how much bitcoin each fund put behind one share at launch. A cheaper share is not better value. Fractional shares let you buy a dollar amount instead of whole shares; Fidelity, Schwab, IBKR and Robinhood all support it on ETFs.
Step 5 — Record your cost basis
Cost basis is the price at which you acquired shares, adjusted for commissions and any returns of capital. It determines your taxable gain or loss when you sell. First-time Bitcoin ETF buyers skip this step more than any other, and the problem shows up months or years later at tax time.
How brokers track it
US brokers report cost basis for covered securities on Form 1099-B at year end. If you hold the shares at a single brokerage and never transferred them in, the broker handles it automatically. Save every trade confirmation anyway. It records the purchase date and price, and it is your backup if the broker's record is wrong, which happens most often after an account transfer.
FIFO vs specific lot
When you own multiple lots (shares bought at different times and prices) and sell only some of them, the IRS requires a consistent accounting method. FIFO (first in, first out) is the default at most US brokers: the oldest shares count as sold first. Specific lot identification lets you choose which shares to sell, for example a high-basis lot to keep the gain small, or a lot bought above today's price to harvest a loss. Most major brokers support specific lot selection at the time of sale. Set your method in the account settings before your first sale. Changing it later can be a paperwork mess.
Form 8949 and Schedule D
Each sale of a Bitcoin ETF in a taxable account generates a line on Form 8949 (Sales and Other Dispositions of Capital Assets), which then rolls into Schedule D. Long-term capital gains (assets held more than 12 months) are taxed at 0%, 15%, or 20% depending on income. Short-term gains (held 12 months or less) are taxed as ordinary income. Bitcoin ETFs held inside an IRA or Roth IRA produce no annual 8949 lines: tax is deferred in a traditional IRA and does not apply in a Roth.
If you buy and sell multiple times in a year, your broker's consolidated 1099 at year-end will summarize the transactions. Verify the cost basis figures match your trade confirmations before filing.
Account type tax comparison
| Account type | Tax on contributions | Tax on growth | Tax on withdrawal | Annual limit |
|---|---|---|---|---|
| Roth IRA | After-tax (no deduction) | None | None (qualified) | $7,500 / $8,600 (50+) |
| Traditional IRA | Pre-tax (deductible) | Deferred | Ordinary income rate | $7,500 / $8,600 (50+) |
| 401(k) — traditional | Pre-tax | Deferred | Ordinary income rate | $24,500 employee deferral (2026) |
| Taxable brokerage | After-tax | Taxed annually (dividends) / at sale (gains) | No restriction | Unlimited |
Common mistakes
- Buying GBTC without checking the fee. The original Grayscale Bitcoin Trust (GBTC) charges 1.50%, six times what IBIT or FBTC charge. It made sense before ETF approval. Today the only reason to hold it is an unrealized loss worth harvesting. The Grayscale Mini Trust (BTC) is a lower-cost alternative at 0.15%.
- Placing a market order at the open. Spreads widen in the first 15 minutes while market makers reprice for overnight bitcoin moves. Use a limit order or wait until 10 a.m. ET.
- Buying a futures ETF instead of a spot ETF. BITO (ProShares Bitcoin Strategy ETF) holds bitcoin futures, not bitcoin. When the futures curve is in contango, rolling contracts costs the fund money the spot price never charges. The difference is explained in spot vs futures Bitcoin ETF.
- Assuming you know how the wash-sale rule applies. If you sell any security at a loss and buy a substantially identical one within 30 days either side, §1091 disallows the loss. Whether shares in a bitcoin grantor trust are "stock or securities" for that purpose is not settled. IBIT's own 10-K calls the tax classification "not free from doubt" and never uses the words "wash sale". Do not plan a harvest around either answer without talking to a tax adviser.
- Relying on old information about your broker. Vanguard's refusal to carry spot Bitcoin ETFs was the best-known restriction in the category, and it ended on 2 December 2025. Broker policies here have changed several times; check the current one before opening a second account you do not need.
FAQ
Can I buy a Bitcoin ETF at any broker?
At the major US brokers, yes. Fidelity, Charles Schwab, E*TRADE, Interactive Brokers, Robinhood, Webull and Merrill Edge all carry spot Bitcoin ETFs. Vanguard was the long-running exception, refusing to carry them from the January 2024 launch until it reversed the policy on 2 December 2025.
How much do I need to start buying a Bitcoin ETF?
There is no minimum at most brokers. Share prices across the twelve US spot Bitcoin ETFs ranged from about $24 to $89 at the close on 23 September 2026, and brokers that sell fractional shares (Fidelity, Schwab, IBKR, Robinhood) allow purchases as small as $1.
Should I buy a Bitcoin ETF in a Roth IRA or a taxable account?
Roth IRA first, if you have contribution room and intend to hold long term: qualified withdrawals are tax-free, where a taxable account owes long-term capital gains tax at 0%, 15% or 20% at sale, plus the 3.8% Net Investment Income Tax for higher earners. The 2026 Roth contribution limit is $7,500, or $8,600 from age 50 (IRS Notice 2025-67). How big the advantage gets depends on your tax rate and the return, so work it out with your own numbers.
Which Bitcoin ETF should I buy?
IBIT (BlackRock, 0.25%) for size and liquidity: it held $43.39bn of net assets at 30 June 2026. MSBT (Morgan Stanley, 0.14%), the Grayscale Mini Trust (0.15%) or Franklin EZBC (0.19%) for the lowest fees. FBTC (Fidelity, 0.25%) if you want the bitcoin held outside the third-party custody market. HODL (VanEck, 0.20%) if you want Gemini in the structure, bearing in mind it names Coinbase Custody as an additional custodian. Most investors do well choosing one fund and leaving it alone.
When is the best time of day to buy a Bitcoin ETF?
Mid-session, between 10:30 a.m. and 3:30 p.m. Eastern Time, has the tightest bid-ask spreads. Avoid the first and last 15 minutes of the trading day, when spreads briefly widen as market makers reprice around bitcoin spot moves and NAV updates.
Do I need to track cost basis myself if my broker reports it?
Your broker reports covered-security cost basis on Form 1099-B, but you should still save every trade confirmation as a backup. If you want to use specific-lot accounting (to minimize gains or harvest losses), you must elect it at your broker before the sale. FIFO is the default and cannot be changed retroactively after a sale settles.
Sources and further reading
- IRS Notice 2025-67, "2026 Amounts Relating to Retirement Plans and IRAs, as Adjusted for Changes in Cost-of-Living", irs.gov.
- IRS Publication 550, "Investment Income and Expenses", and the Form 8949 instructions, irs.gov.
- Forms 10-Q for the quarter ended 30 June 2026 for the US spot Bitcoin ETFs, sec.gov/Archives/edgar.
- Internal: Best brokerage for Bitcoin ETF, Bitcoin ETF in a Roth IRA, Expense ratios compared, Bitcoin ETF vs spot Bitcoin.
For information only. Not investment advice.
 ETH
 SOL
 XRP
 HYPE
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC