The three US HYPE ETFs charge 0.29–0.34% and pass on 1.18–1.68% of staking reward. Staking the token yourself earns the full ~2.25% and unlocks fee discounts, at the price of a wallet and a seven-day unstaking queue.
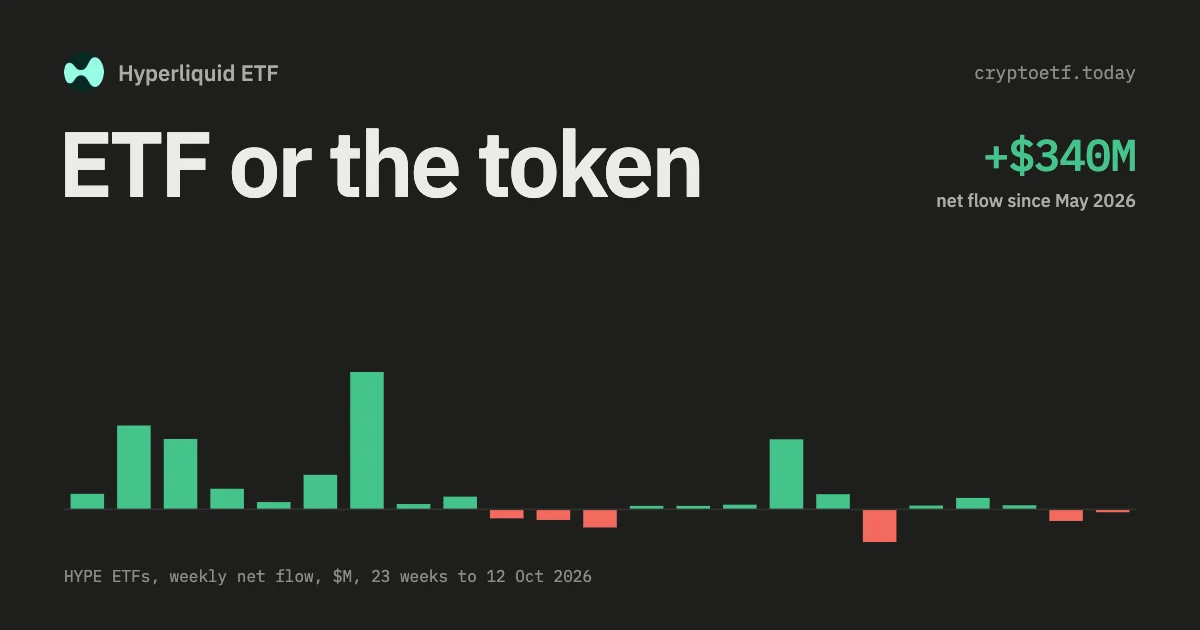

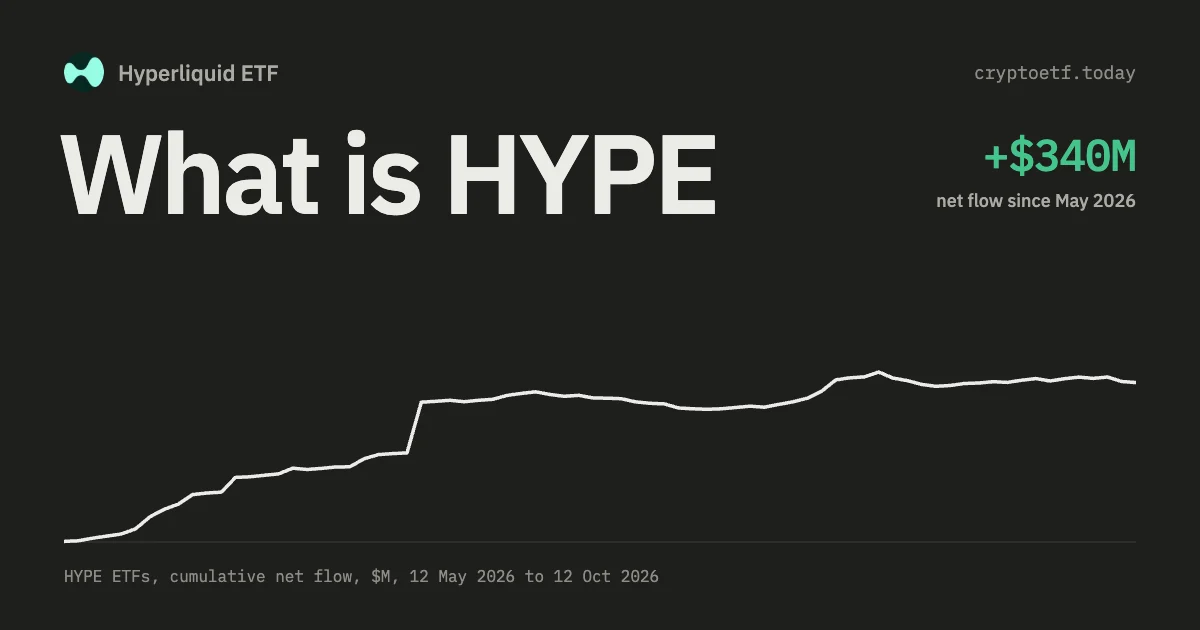
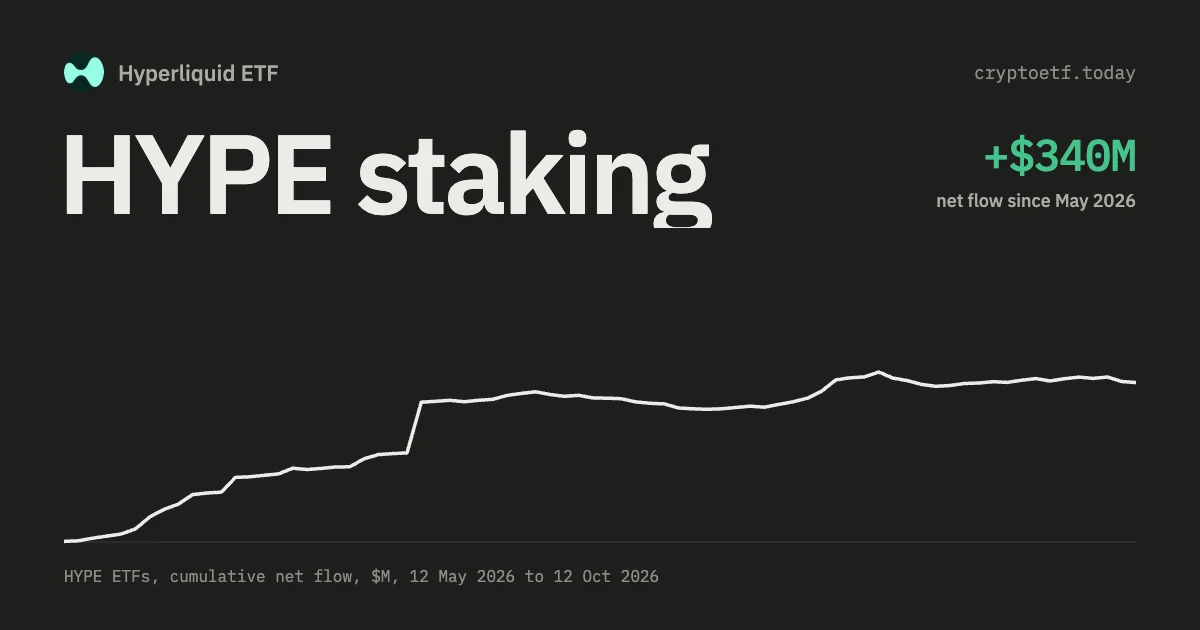
Hyperliquid ETF flows, live
as of Fri 20 Nov · updated every trading dayContents · 12 sections
- The three funds you would be choosing between
- The cost comparison, done properly
- What only the token gives you
- What only the fund gives you
- Tracking error: the cost nobody quotes
- The tax dimension
- The risks are different, not smaller
- Which one for which person
- The case nobody makes: both
- How this compares with Bitcoin
- FAQ
- Sources and further reading
Updated 19 November 2026. Fund figures as of 18 November 2026 from the cryptoetf.today fund registry, staking tracker and flow table; staking disclosures dated 21–22 October 2026 (BHYP: 17 November 2026).
TL;DR. Three US ETFs hold HYPE: Grayscale HYPG (0.29%), 21Shares THYP (0.30%) and Bitwise BHYP (0.34%). After the sponsor's cut of staking rewards they report net staking yields of 1.68%, 1.31% and 1.18%. Staking the token yourself earns the full reward, which BHYP's and HYPG's issuers put at 2.25% gross, unlocks trading fee discounts on Hyperliquid and gives you a vote. The ETF wins on retirement accounts, on custody, and on selling in one session instead of waiting out a seven-day unstaking queue. If you trade on Hyperliquid, the token fits. If your money sits in an IRA, a fund is the practical route.
The three funds you would be choosing between
On 18 November 2026 the US HYPE funds held $310.5m between them, about 4.66m tokens or 1.96% of HYPE's circulating supply. Each one stakes, and each one pays staking income out in cash.
| HYPG (Grayscale) | THYP (21Shares) | BHYP (Bitwise) | |
|---|---|---|---|
| Sponsor fee | 0.29% | 0.30% | 0.34% |
| Net assets | $152.6m | $37.0m | $120.9m |
| Share staked | 88.93% | 76.62% | 68.65% |
| Net staking yield (issuer) | 1.68% | 1.31% | 1.18% |
| Rewards kept by holders | 75% | 70% | 75%* |
| Payouts | Cash, monthly | Cash, quarterly | Cash, quarterly |
*Bitwise's 10-Q for the quarter to 30 June stated 12% of staking rewards to the sponsor and its agents; its prospectus and the 10-Q for the quarter to 30 September (filed 13 November 2026) state 25%, so holders keep 75%. Issuers compute these yields in slightly different ways and on different dates, so read small gaps as noise; they are not a forecast or a guaranteed return to holders, and they are a yield on the fund's HYPE, not on the ETF's market price. Fund-by-fund detail is on the crypto ETF staking tracker, and the full three-way comparison is in BHYP vs THYP vs HYPG.
The cost comparison, done properly
Start with the number people quote and then add the ones they don't. Assume $10,000 held for a year and a 2.25% gross staking reward, the rate Grayscale disclosed on 22 October 2026 and Bitwise showed on 17 November.
| Per $10,000 a year | HYPG | THYP | BHYP | Token, staked yourself |
|---|---|---|---|---|
| Sponsor fee | −$29 | −$30 | −$34 | $0 |
| Staking income | +$168 | +$131 | +$118 | +$225 less validator commission |
| Trading fee discount | None | None | None | Tiered, on Hyperliquid trades |
| Entry cost | Bid-ask spread on a small fund | Exchange fee and on-chain transfer | ||
| Carry before price | ~+$139 | ~+$101 | ~+$84 | Up to ~+$225 |
Against the cheapest fund, direct staking comes out ahead by up to about 85 basis points a year, less whatever the validator you pick charges. Against BHYP the gap is wider. These are the issuers' disclosed rates applied to a round number; real staking rewards move with network activity, so read the table as a ratio, not a forecast.
Two things change the picture for a real holder. The fund's staking income arrives as cash distributions, which in a taxable account are taxable when paid. And the token's figure assumes you stake all of it all the time, with no mistakes. The table can't price the rest of the trade.
What only the token gives you
HYPE isn't a passive asset. On the platform it does three jobs a fund share can't:
- Fee discounts. Hyperliquid's documentation sets staking tiers that cut trading fees as the staked amount grows, from 5% off at the smallest tier to 40% at the largest (500,000 HYPE at the time of writing). For an active trader that dwarfs every other number in this article. Check the current tier table before relying on it.
- Market deployment. Under HIP-3, staked HYPE lets a builder launch new perpetual markets. That's a business, not a yield.
- Governance. Votes belong to holders. A fund's tokens are the sponsor's to vote or abstain.
None of this reaches a shareholder. The ETF is a claim on the price and a share of the staking reward, and that's the whole of it. The mechanics are in what Hyperliquid and HYPE actually do.
What only the fund gives you
- Retirement accounts. An IRA or 401(k) can hold an ETF. It generally cannot hold HYPE. For a large share of US investors this ends the discussion.
- No key management. No seed phrase, no bridge, no exchange account, no chance of a self-inflicted total loss.
- Exit in one session. Sell shares during market hours and settle T+1. Staked tokens go through a seven-day unstaking queue.
- Clean reporting. One line on a brokerage statement, standard cost-basis reporting, no reconciling on-chain rewards at tax time.
- Institutional mandates. Plenty of entities may buy listed securities and may not touch a self-custodied token.
The liquidity point is often stated backwards. The unstaking queue applies to the fund's assets, not to your shares. You can sell HYPG at 10:31am and be done; the fund handles unbonding on its own schedule. That service has had a real workout lately. Over the 30 days to 18 November the three funds met $47.4m of net redemptions (BHYP −$29.9m, THYP −$16.5m, HYPG −$1.1m) with roughly two thirds to 89% of their tokens staked. Shareholders who sold in that stretch dealt with an exchange, not the queue. The daily series is on the Hyperliquid ETF flow tracker.
Tracking error: the cost nobody quotes
A fund share is not the token, and over time the two diverge for reasons beyond the fee. Three sources of drift matter here.
Trading hours. HYPE trades around the clock; the funds trade six and a half hours a day, five days a week. A weekend move shows up as a gap at Monday's open, so the fund's chart and the token's chart never quite match even when the fund tracks perfectly.
Premium and discount. On funds holding between $37m and $153m, the share price can drift from the value of the underlying HYPE before an authorised participant steps in. Buy at a premium and sell at a discount and you've paid a cost that appears in no fee table. Each fund's price page, such as the HYPG price page, shows how it has traded.
Staking timing. Because all three funds pay rewards out in cash, the HYPE behind each share does not compound the way staked tokens in your own wallet can. Between payouts, rewards can pile up inside the fund. Our estimate from daily issuer snapshots shows BHYP's tokens per share growing at about 1.07% a year between 10 September and 13 November, a period with no Bitwise payout on our record, while THYP's stayed flat (−0.04% a year) after its September distribution.
Direct ownership has none of these. One token is one token, priced continuously, with rewards landing in your account. Simplicity is part of what you're buying.
The tax dimension
In a US taxable account, both routes trigger a gain or loss on disposal. The differences show up in the yield.
Staking rewards received directly are generally income when received, at their value on that date, and every reward event creates a new cost basis lot. Anyone who has reconciled a year of on-chain staking rewards knows what that costs in time.
Inside a fund the income doesn't vanish either. HYPG pays monthly; its last payout was $0.035625 per share, ex-date 3 November 2026. THYP pays quarterly; its last was $0.19136 per share, ex-date 29 September. BHYP is set up for quarterly cash payouts. Each one is a taxable event in a taxable account, but the fund does the reporting and you get one form instead of a spreadsheet of on-chain transactions.
The character of crypto staking income remains contested in several jurisdictions, so treat none of this as settled and read each fund's tax disclosure. What is clear: inside an IRA the whole question disappears, which is the strongest structural argument the wrapper has.
The risks are different, not smaller
Both routes carry the same market risk. HYPE closed between about $68 and $96 on our daily series from 19 August to 18 November 2026, peaking on 22 September, and a 50% drawdown is possible in either structure. ETF buyers as a group estimated average entry near $65.69 per token, leaving them about 1.5% in profit on 18 November, per the ETF cost basis tracker. That cushion is thin.
Holding the token, the failure modes are yours. A lost key, a phishing signature, a bridge exploit or a bad validator all cost you principal, and none of them has a customer service line. Self-custody is a skill, not a checkbox.
Holding the fund, the failure modes are institutional. The sponsor could mismanage staking, a custodian could fail, heavy redemptions could push a fund with most assets staked onto its liquidity reserve and a slow unstaking queue, or the product could close if it stays small. THYP, at $37.0m and shrinking, is the one to watch on that last count. None of these is likely. All of them are outside your control, which is the trade you're making.
A structural point: US spot crypto ETPs are not registered under the Investment Company Act of 1940, so they lack the protections that apply to ordinary mutual funds and ETFs. The prospectuses say this plainly, and it's the sentence most buyers skip.
Which one for which person
| If you... | Choose | Because |
|---|---|---|
| Trade on Hyperliquid | Token | Fee discounts up to 40% outweigh every other cost |
| Invest through an IRA or 401(k) | ETF | The token generally can't be held there |
| Want maximum yield and will self-custody | Token | Keeps the full reward, no sponsor cut |
| Want a fund with the highest disclosed staking yield | HYPG | 1.68% net and the lowest fee, 0.29% |
| Don't want to run a wallet | ETF | Custody, staking and reporting are handled |
| Manage other people's money | ETF | Mandates and custody rules usually require it |
| Want options on the position | ETF (THYP) | THYP was the first HYPE fund with listed options |
This is a map of trade-offs, not a recommendation for any particular account.
The case nobody makes: both
These aren't mutually exclusive, and for someone with money in more than one account type, splitting is often the sensible answer. Hold the fund in the IRA, where it's the only permitted route and the tax friction of staking income goes away. Hold the token in the taxable side if you actually use the platform, where the fee discount and the full reward accrue to you.
That combination captures most of what each structure does well. It also doubles the number of things to track, which is a real cost for anyone who won't keep up with it.
How this compares with Bitcoin
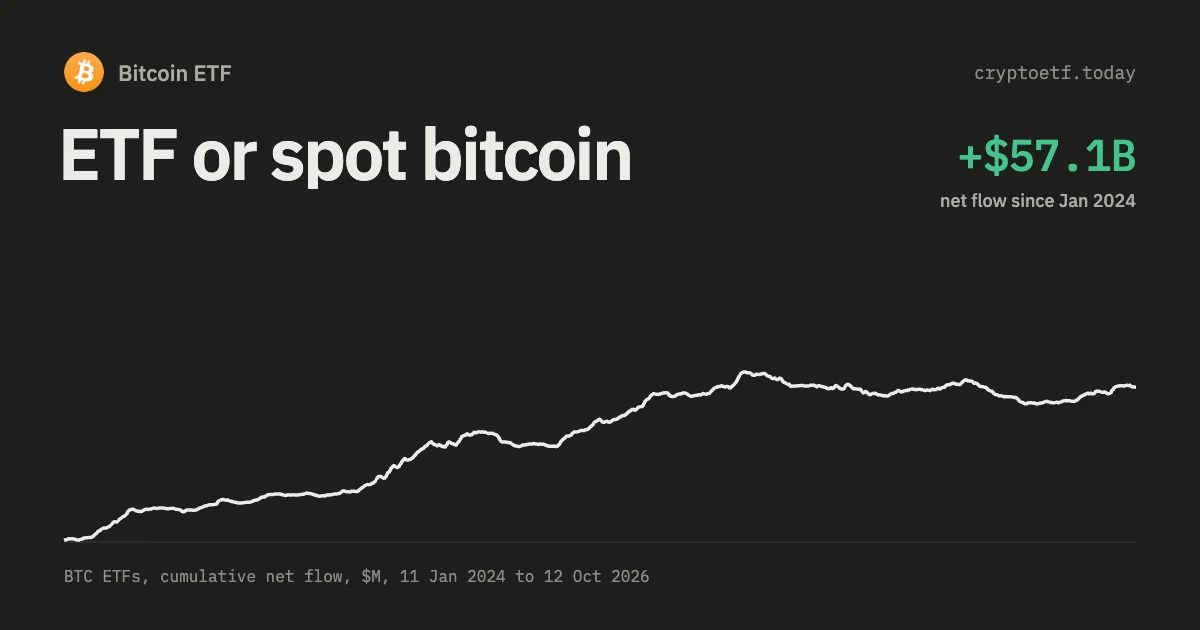
The same decision on Bitcoin is simpler, because BTC produces nothing. Most US spot Bitcoin funds charge between 0.14% and 0.25% a year, and the only counterargument is self-custody and round-the-clock trading, as we set out in Bitcoin ETF versus spot Bitcoin.
HYPE adds two things to that calculation: a staking reward the sponsor takes a cut of, and platform utility the wrapper can't deliver at all. Both push toward the token for anyone who can hold it. The wrapper's advantage narrows to access and convenience, which for the accounts most people actually invest through still decides it.
FAQ
Is it cheaper to buy a HYPE ETF or the token?
The token, on carry. Staking HYPE yourself earns the full reward, which Bitwise and Grayscale put at 2.25% gross in October 2026. The funds charge 0.29–0.34% and report net staking yields of 1.18–1.68%, so the gap against the cheapest fund is up to about 85 basis points a year before validator commission and any trading fee discounts.
Which HYPE ETF has the lowest fee and highest staking yield?
As of November 2026, Grayscale HYPG on both counts: a 0.29% sponsor fee and a 1.68% net staking yield as disclosed on 22 October 2026. 21Shares THYP charges 0.30% with a 1.31% net yield, and Bitwise BHYP 0.34% with 1.18%.
Do HYPE ETF holders get the staking fee discount on Hyperliquid?
No. Fee discounts attach to the wallet doing the trading, based on how much HYPE it has staked. A fund shareholder has no wallet on the platform and gets nothing.
Can I hold HYPE in an IRA?
Generally not directly. Retirement accounts can hold exchange-listed securities, so a HYPE ETF is the practical route, and most custodians allow crypto ETPs. This is the strongest single argument for the fund.
How fast can I sell in each case?
ETF shares sell during US market hours with T+1 settlement, whatever share of the fund is staked. Unstaked tokens sell any time on an exchange, but staked HYPE first goes through a seven-day unstaking queue.
Do HYPE ETFs pay out staking rewards?
Yes, in cash. HYPG pays monthly (last $0.035625 per share, ex-date 3 November 2026), THYP quarterly (last $0.19136, ex-date 29 September 2026), and BHYP is set up for quarterly payouts. In a taxable account each payout is generally taxable when received.
Can I own both?
Yes, and for many people that is the sensible answer: the fund inside a retirement account where the token cannot go, and the token in a taxable account if you actually use the platform and want the fee discounts.
Sources and further reading
- Hyperliquid documentation: staking tiers, fee discounts and the unstaking queue — hyperliquid.gitbook.io.
- Grayscale, HYPG fee, staking terms and distributions — etfs.grayscale.com.
- 21Shares, THYP fund page — 21shares.com.
- Bitwise, BHYP fund page — bhypetf.com.
- IRS guidance on staking rewards and digital assets — irs.gov.
- Internal: staking inside the wrapper, 21Shares THYP review, Grayscale HYPG review, all US crypto ETFs.
For information only. Not investment advice.
 BTC
 ETH
 SOL
 XRP
 LINK
 HBAR
 AVAX
 DOGE
 LTC
 SUI
 DOT
 BNB
 NEAR
 TRX
 ZEC